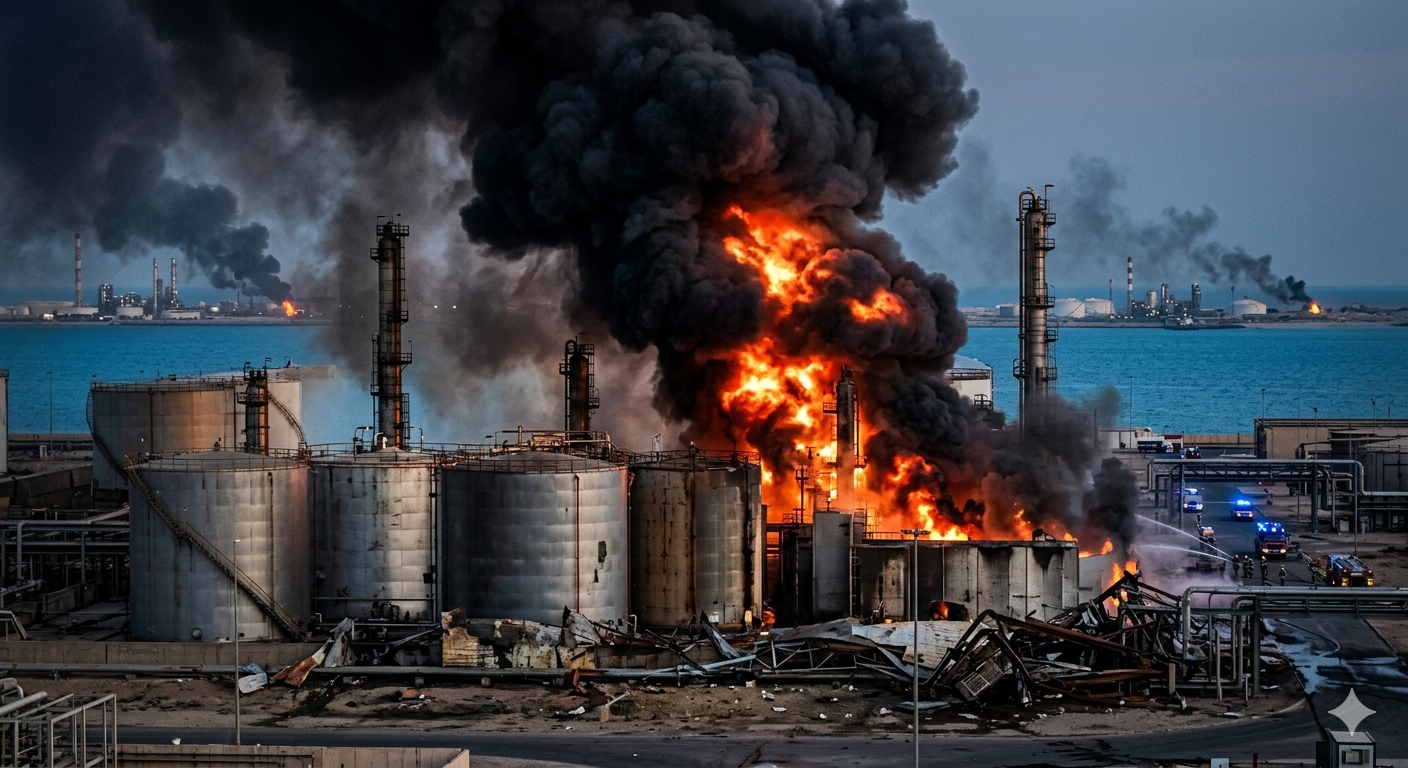
| Day 17–21 of the US-Iran War | Brent $107→$112 | S&P −3.0% WoW | Nasdaq −4.4% WoW | VIX 29→31 |
This was the week the war stopped being background noise and became the dominant macro variable. What started Monday with cautious optimism around FOMC and a ceasefire whisper ended Friday with Kuwait’s refineries on fire, Brent at $112, the Nasdaq in correction territory, and the Fed explicitly warning that inflation “isn’t coming down as much as we had hoped.” The week delivered three distinct shocks, geopolitical, monetary, and energy, and each one compounded the last.
Executive Summary | Five Days That Changed Everything
| Day | Date | Key Events | S&P |
|---|---|---|---|
| Monday (Day 17) | Mar 16 | Cautious open. Brent $104. FOMC preview. Mojtaba Khamenei issues hawkish first statement. Trump sends mixed signals on China summit. | +0.25% |
| Tuesday (Day 18) | Mar 17 | Israel assassinates Ali Larijani, invades Lebanon. Two-front war confirmed. NVIDIA GTC: $1T order book. Markets flat on offsetting forces. | −0.3% |
| Wednesday (Day 19) | Mar 18 | Iran retaliates: 100+ Israeli targets, UAE Fujairah terminal fire, US Embassy Baghdad hit. PPI shock: +0.7% MoM (est +0.3%). FOMC holds at 3.50–3.75%, dot plot shows 1 cut (was 2). | −0.9% |
| Thursday (Day 20) | Mar 19 | Powell presser: “Not making progress on inflation.” Dow −768. Israel + US strike South Pars gas field. Micron crushes: EPS $12.20 vs $9.31 est. MU sells off 5% on profit-taking. | −1.5% |
| Friday (Day 21) | Mar 20 | Kuwait refineries (730K bpd) on fire. Iraq force majeure declared. Pentagon preps ground troops. Brent $112. COHR +15.4%, LITE +12%. FedEx beats. | −1.5% |
Weekly Performance Scorecard
| Index / Asset | Mon Open | Fri Close | WTD Chg | YTD Chg | Note |
|---|---|---|---|---|---|
| S&P 500 | ~6,680 | 6,506 | −3.0% | −9.1% | Worst week of 2026; 5th down week of 6 |
| Nasdaq Composite | ~22,100 | 21,647 | −4.4% | ~−10.9% | In correction; growth premium eroded |
| Dow Jones | ~46,660 | 45,577 | ~−2.3% | ~−7.2% | Kuwait refineries + ground troop prep |
| Russell 2000 | ~2,050 | correction | ~−2.5% | ~−13.5% | Official correction; small caps worst hit |
| Brent Crude | ~$107 | $112.10 | +7.6% | — | 5th consecutive weekly gain; Kuwait fire |
| VIX | 29 | 31 | +2pt | — | Structurally elevated; no floor visible |
| Gold | ~$3,250 | $3,305+ | +~1.7% | — | ATH zone; stagflation + war bid |
| 10-Yr Yield | ~4.28% | ~4.45% | +17 bps | — | FOMC dot plot repricing; inflation fear |
War Timeline | Day 17 to Day 21
| Day | Date | Event |
|---|---|---|
| Day 17 | Mon Mar 16 | FOMC week opens. Mojtaba Khamenei’s first statement: maximally hawkish. No ceasefire opening. NVDA GTC begins. |
| Day 18 | Tue Mar 17 | Israel assassinates Ali Larijani (Iran’s national security chief), his son Morteza, and Basij commander. Israel invades Lebanon south of Litani River. 1M displaced. Two-front war confirmed. |
| Day 19 | Wed Mar 18 | Iran IRGC retaliates: 100+ Israeli targets hit. UAE Fujairah terminal fire. Saudi defences intercept 6+ drones. US Embassy Baghdad hit directly. PPI +0.7% MoM. FOMC holds; dot plot: 1 cut. |
| Day 20 | Thu Mar 19 | Powell: “Not making progress on inflation.” Dow −768. US + Israel strike South Pars gas field. Iran publishes Gulf hit list (Samref, Al Hosn, Bapco). MU beats massively AH (+8%). |
| Day 21 | Fri Mar 20 | Kuwait: Mina Al-Ahmadi + Mina Abdullah refineries struck (730K bpd offline). Iraq declares force majeure. Pentagon preps ground troops. Brent $112. COHR +15.4%, LITE +12%. |
War Signal Tracker | End-of-Week Assessment
| Signal | Detail | Direction |
|---|---|---|
| Larijani assassination | Removed last diplomatic off-ramp; no Iranian negotiating counterpart | BEAR |
| Lebanon ground invasion | Two-front war confirmed; expanding, not contracting | BEAR |
| Iran retaliation | 100+ targets, UAE, Saudi, US Embassy Baghdad | BEAR |
| South Pars strike | World’s largest gas field hit; domestic Iranian supply compromised | BEAR |
| Kuwait refineries | 730K bpd offline; no restart timeline | BEAR |
| Iraq force majeure | 1M+ bpd Basra crude at risk | BEAR |
| Pentagon ground troop prep | Qualitative escalation; full regional war scenario on table | BEAR |
| COHR +15.4%, LITE +12% | AI immune to war macro; optical interconnects in demand | BULL |
Assessment: 7 BEAR / 1 BULL / 0 NEUTRAL. The war posture deteriorated materially this week. The assassination of Larijani removed the only diplomatic off-ramp. Energy supply disruption is now structural, not episodic.
FOMC Recap | The Hawkish Hold That Changed Everything
🏛️ FOMC Decision: Hold at 3.50–3.75%. 11-1 Vote. Dot Plot: 1 Cut in 2026. Powell: “Not making progress.”
The Fed delivered the most hawkish hold of the current cycle. The dot plot reduced 2026 rate cut projections from 2 to 1. The inflation forecast was raised to 2.7% for 2026. Powell’s press conference removed all ambiguity: “We’re not making as much progress on inflation as we had hoped.” The dissenter (Miran) voted for a cut, meaning the committee is divided, but not in the direction markets wanted.
| Projection | Dec 2025 | Mar 2026 | Signal |
|---|---|---|---|
| 2026 Rate Cuts | 2 | 1 | Hawkish |
| 2026 Inflation (PCE) | 2.5% | 2.7% | Hawkish |
| 2026 GDP | 2.1% | ~1.8% | Lowered |
| Dissenter | — | Miran (for cut) | Divided |
Earnings Spotlight | Micron (MU) — The AI Memory Monster
| Metric | Estimate | Actual | Beat |
|---|---|---|---|
| EPS | $9.31 | $12.20 | +31% |
| Revenue | $20.07B | $23.86B | +19% |
| FCF | — | $6.9B (record) | — |
| Q3 Revenue Guide | — | $33.5B | — |
| Q3 Gross Margin | — | 81% | — |
Despite the blowout, MU fell ~5% after-hours Thursday and continued lower Friday. Classic “sell the news” after a 65% YTD run into earnings. Analyst targets surged: Wells Fargo to $550 (from $470), Barclays to $670 (from $450). The pullback is a gift; this is the best fundamental story in semis. HBM4 shipping to NVIDIA for Vera Rubin confirms the $1T order book narrative is real.
Sector Spotlight | Photonics — The Breakout Week
S&P 500 inclusion. COHR and LITE join the index on Monday March 23. Mechanical passive buying estimated at $2–4B combined. This is a date-certain catalyst.
NVIDIA partnerships. $2B investment in each company. Multi-year purchase commitments for advanced laser components and optical interconnects. This is not a one-off.
OFC 2026. Industry conference in LA confirmed surging demand for 1.6T and 3.2T optical modules. AI datacenter buildout requires exponentially more photonic capacity.
Valuation. Despite the rally, both COHR and LITE trade at reasonable multiples relative to growth. COHR at ~28x forward P/E with 40%+ revenue growth. LITE at ~25x with similar trajectory.
| Name | WTD Move | S&P 500 Add | Key Catalyst |
|---|---|---|---|
| COHR (Coherent) | +15.4% | Mar 23 | OFC 2026 + NVDA multi-billion partnership |
| LITE (Lumentum) | +12% | Mar 23 | OFC 2026 + NVDA multi-billion partnership |
Other Notable Earnings This Week
NVDA (GTC Week): $1T order book announced. Groq 3 LPU, Vera Rubin chips, NemoClaw AI agents. Stock volatile but structurally bullish.
Accenture (ACN): Beat estimates but gave cautious guidance citing enterprise IT spending delays. AI consulting bookings strong but not enough to offset macro headwinds.
Nike (NKE): Missed revenue estimates. China sales weak. Inventories elevated. Worst performer in Dow this week.
Oil & Energy Crisis | The Supply Shock Is Now Structural
Brent crude rose 7.6% this week to $112.10, its fifth consecutive weekly gain and highest level since 2022. The supply picture deteriorated dramatically:
| Facility | Capacity | Status |
|---|---|---|
| Kuwait Mina Al-Ahmadi | 730K bpd combined (with Abdullah) | Offline; IRGC drone strike Fri |
| Iraq Basra | 1M+ bpd | Force majeure declared |
| UAE Fujairah | major storage hub | Terminal fire; storage capacity compromised |
| South Pars (Iran) | ~5% global LNG | US + Israel strike Thu; export capacity hit |
| Hormuz Strait | ~20% global oil flow | Partially disrupted; Iran targeting Gulf infra |
Goldman Sachs says oil may stay in triple digits for years if the war continues. The energy crisis is no longer a tail risk; it is the base case.
Forward Look | Week of March 23–27, 2026
Next week brings a light data calendar but heavy event risk. Key themes:
S&P 500 rebalance. COHR, LITE, and VRT added Monday. Expect heavy volume and potential short squeezes in all three names.
PCE inflation (Friday). February core PCE, the Fed’s preferred gauge, is the marquee data point. Consensus 0.3% MoM. A hot print would seal the coffin on any 2026 cuts.
War Week 4. No diplomatic channels open. The Larijani assassination closed the last one. Watch for Iranian escalation at Hormuz, potential ground force deployment, and nuclear facility targeting.
Earnings. Lighter week but GameStop (GME), Lululemon (LULU), and Dollar Tree (DLTR) report. Consumer health is the key question.
| Day | Time (ET) | Event | Priority |
|---|---|---|---|
| Mon Mar 23 | Open | S&P 500 rebalance: COHR, LITE, VRT added | HIGH |
| Mon Mar 23 | All Day | War Day 22: Post-Kuwait / Iraq escalation watch | HIGH |
| Tue Mar 24 | 9:00 AM | S&P/Case-Shiller Home Price Index (Jan) | MED |
| Tue Mar 24 | 10:00 AM | Consumer Confidence (Mar) — post-FOMC sentiment | HIGH |
| Wed Mar 25 | 8:30 AM | Durable Goods Orders (Feb) — capex signal | MED |
| Wed Mar 25 | AMC | GME Earnings — consumer health check | MED |
| Thu Mar 26 | 8:30 AM | Weekly Jobless Claims | MED |
| Thu Mar 26 | AMC | LULU Earnings — premium consumer resilience | HIGH |
| Thu Mar 26 | AMC | DLTR (Dollar Tree) — value retail; consumer squeeze | HIGH |
| Fri Mar 27 | 8:30 AM | Core PCE (Feb) — Fed’s preferred inflation gauge | HIGH |
Bottom Line | The Worst Week of 2026. And It Might Get Worse.
Three shocks in five days: a war that went from bad to catastrophic (Larijani killed, Lebanon invaded, South Pars struck, Kuwait burning), a Fed that closed the door on rate cuts (1 cut, maybe 0, inflation “not coming down”), and an energy crisis that is now structural (2M+ bpd offline, no end in sight). The S&P lost 3.0%, the Nasdaq entered correction, the Russell 2000 is near bear market, and Brent closed at $112.
But inside this wreckage, there are pockets of extraordinary strength. Micron delivered the earnings beat of the cycle. Photonics stocks rallied 12–15% against a market down 3%. FedEx beat and raised. The AI secular story is not dead; it’s just being tested by the most hostile macro environment since 2022.
Week 4 begins with no ceasefire, no off-ramp, and Friday’s core PCE as the next landmine. Own the right names. Hedge the rest. This is not the time for complacency.
DISCLAIMER: For internal research purposes only. Market data from Bloomberg, CNBC, Yahoo Finance, TheStreet, TradingEconomics as of Sat Mar 21, 2026. War updates from Al Jazeera, CNN, Reuters, NPR, CBS News, CNBC, FDD Long War Journal. FOMC data from Federal Reserve (03/18/2026). MU earnings from Micron IR, CNBC. COHR/LITE data from StockTitan, Seeking Alpha, 24/7 Wall St. FDX from FreightWaves, CNBC. Oil from CNBC, OilPrice.com, Goldman Sachs Research. Goldman Sachs oil outlook from USNews, Goldman research note.