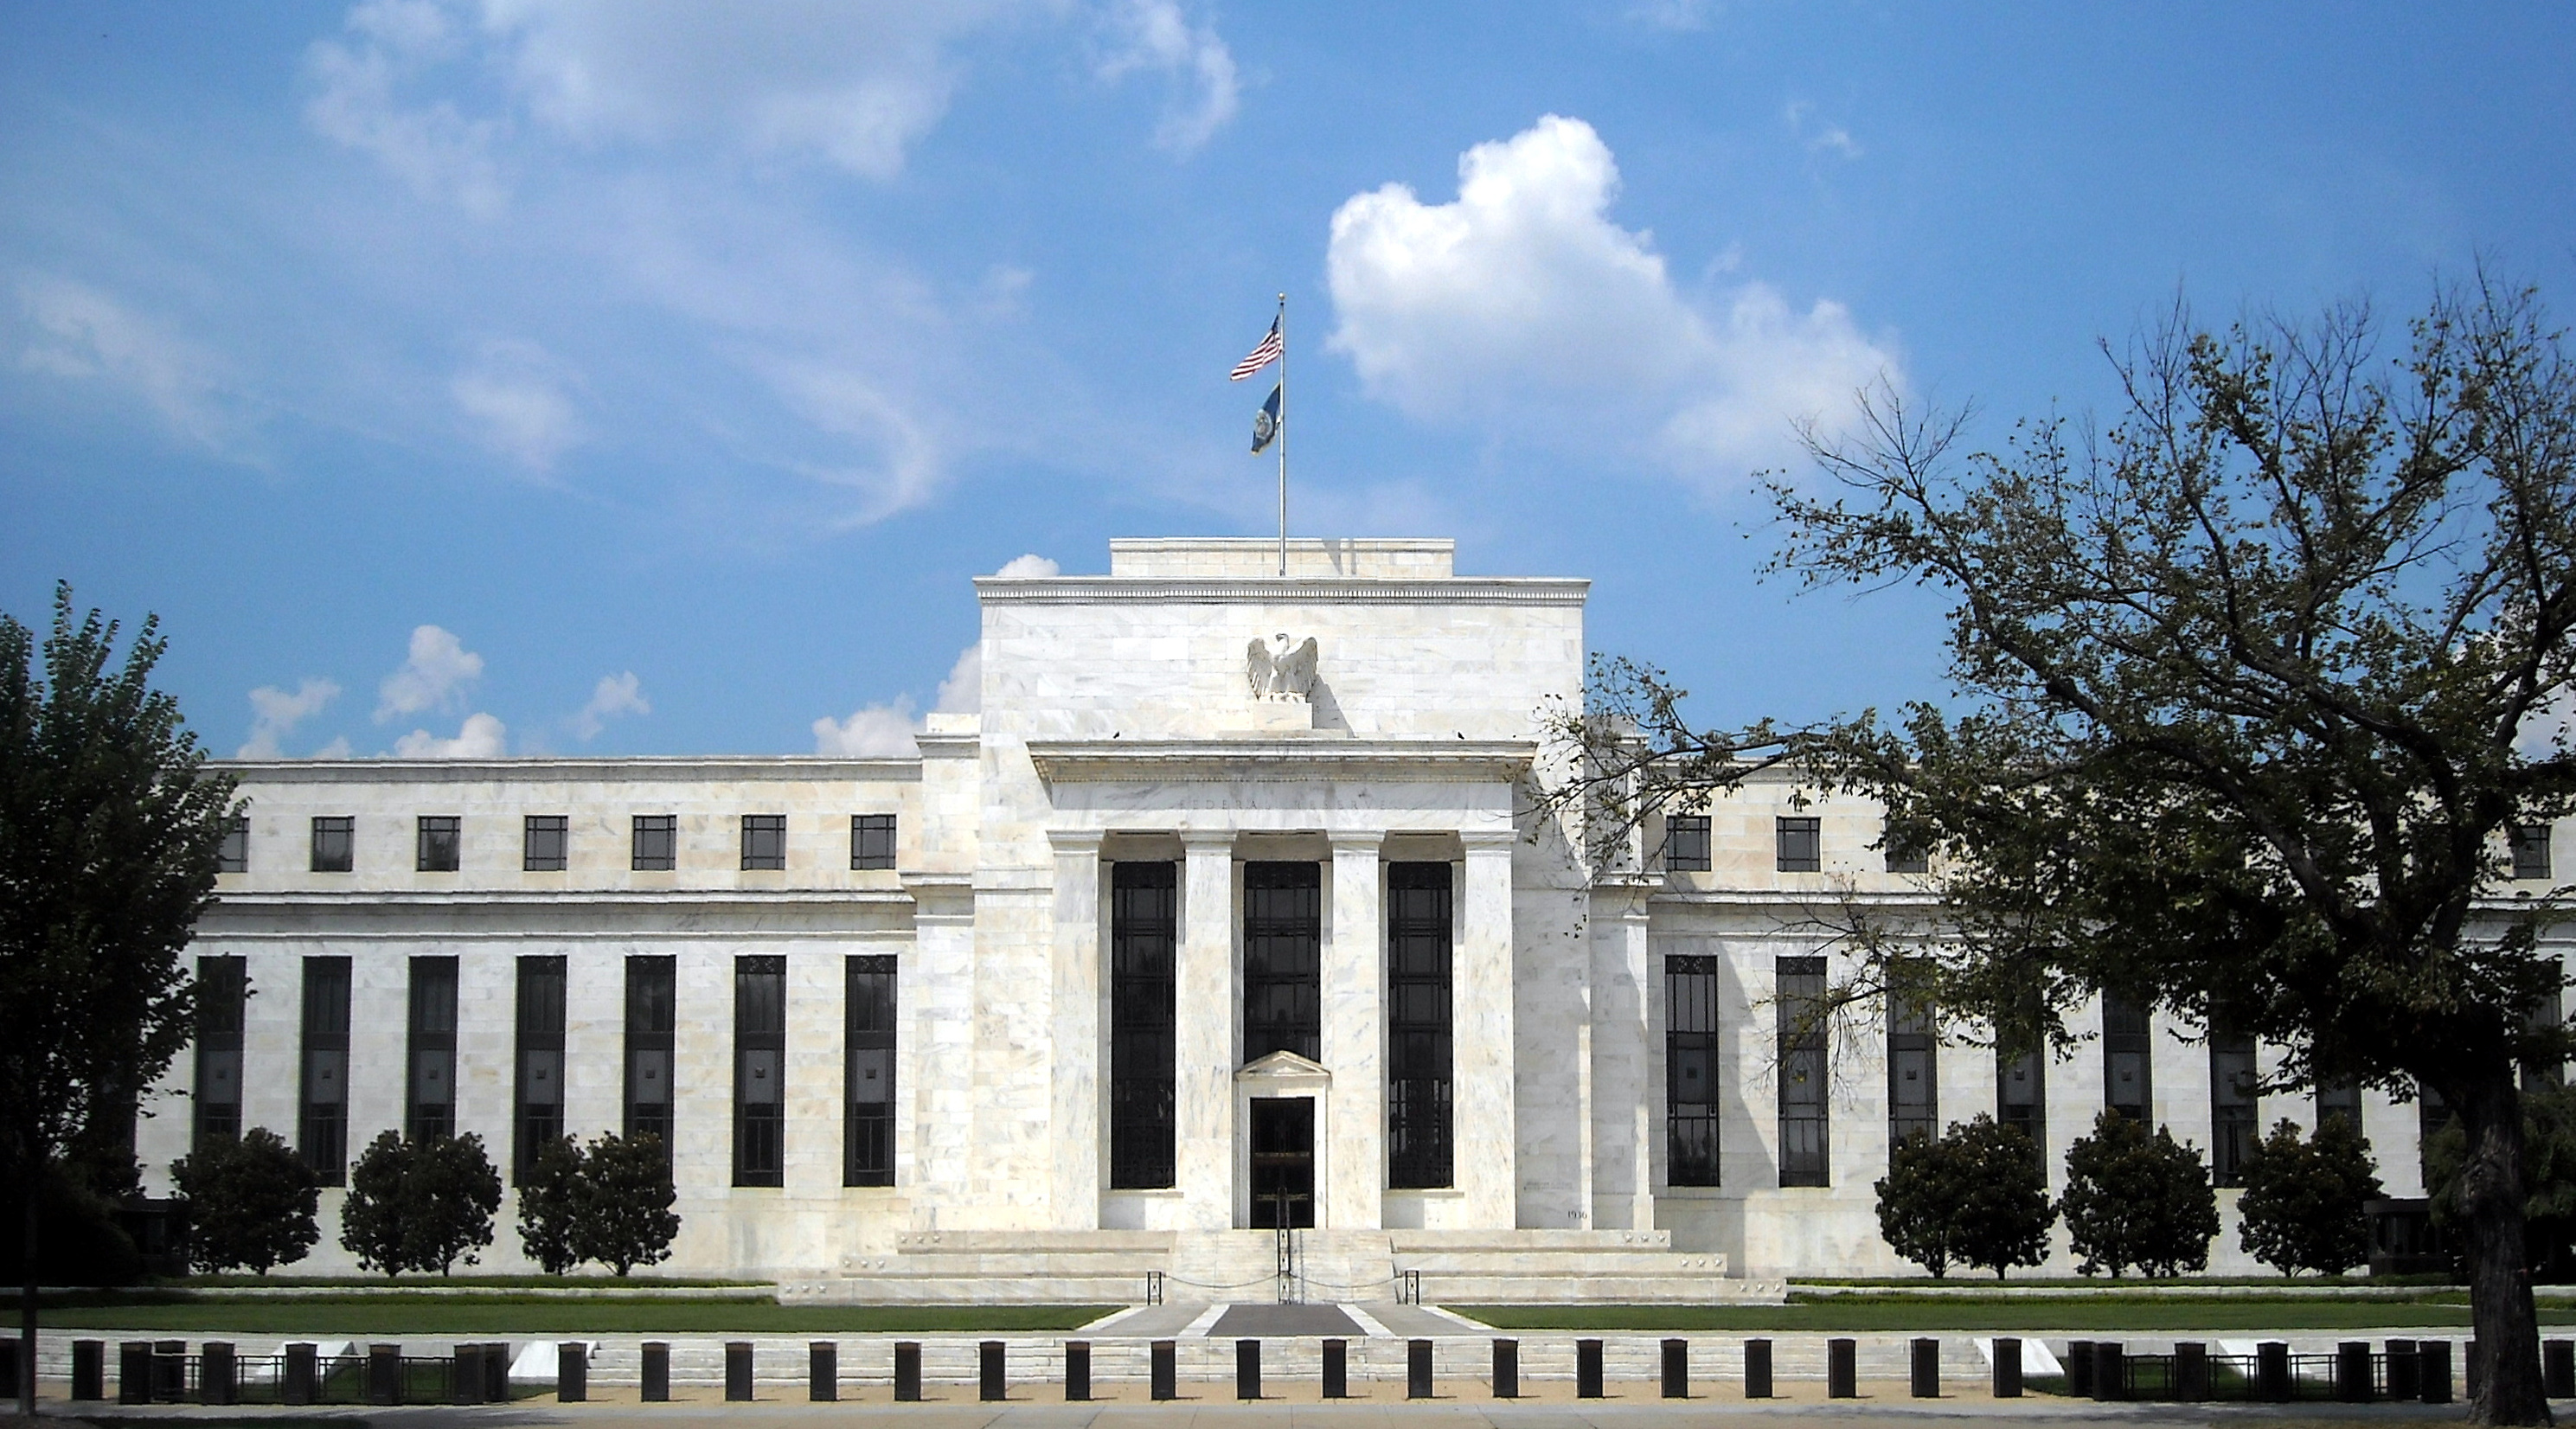
Friday pre-market, 8:30 AM ET, with the US complex trading firmly higher on a constructive risk-on tape that is digesting four overlapping signals: the cleanest single Iran de-escalation rhetoric of the week from Tehran’s “narrowed gaps” framing on the US peace proposal, a 2.7 percent reversal higher in the Brent curve overnight on a fresh Hormuz toll twist out of an Oman-mediated Iranian framework leak, a string of clean corporate beats from Deere ($6.55 vs $5.81), Ross Stores ($2.02 vs $1.70), Ralph Lauren ($2.80 vs $2.54) and Williams-Sonoma ($1.93), and the historic 11 AM ET Warsh swearing-in at the White House as the 17th Federal Reserve Chair, the first such ceremony at the executive residence in 40 years. S&P 500 e-mini sits at 7,475, up 0.40 percent on the deal-optimism tape; Nasdaq 100 e-mini at 26,395, up 0.40 percent on the duration relief and broad-based AI cohort hold; Dow futures lead at 50,625, up 0.70 percent or roughly 340 points on the cyclical cohort lift from the Deere print and the constructive Iran narrative. The 10Y settled at 4.55 percent, three basis points off the Thursday 4.58 print on the deal-optimism duration bid, and the 30Y at 5.07 percent is also three basis points lower, the cleanest single duration bid of the post-FOMC-minutes week. WTI is bid 1.9 percent to $98.18 and Brent is bid 2.7 percent to $105.29 after Thursday’s settlement at $96.35 WTI and $102.58 Brent, the third straight session of declines that compressed the Brent curve from $109 Monday morning to $102 Thursday close on the cumulative diplomatic glide path before the Friday morning Hormuz-toll headline reset positioning. Tehran via Foreign Minister Araghchi said the latest US text “narrowed the gaps to some extent” and confirmed Tehran is in active review, with the leaked positioning showing Iran offering a 12-year nuclear program suspension against the US demand for at least 20 years, plus the bridge gap on uranium-stays-in-country that Khamenei reinforced Wednesday evening. The Iran-Oman Hormuz toll framework leak overnight, reported by multiple wires as a formalization of Tehran’s control over maritime traffic through the strait via a permanent fee mechanism, was the binding bearish overlay that drove the Brent bounce, and Trump’s Truth Social response that the waterway “should remain open, free, and without toll charges” is the structural rejection that prevents the toll framework from advancing as a settlement provision. Pakistan Army Chief Asim Munir’s Thursday Tehran visit concluded with mediators “finalizing an agenda” for resumed direct US-Iran negotiations as early as next week, and the parallel release of 20 Iranian sailors via the Pakistan channel is the cleanest single goodwill signal of the mediation track. Deere reported Q2 FY26 BMO at $6.55 EPS versus the $5.81 consensus (12.7 percent beat), worldwide sales of $13.37 billion (plus 5 percent), with the Small Ag and Turf segment lifting 16 percent on shipment volumes and FX, and Construction and Forestry net sales jumping 29 percent on the same dynamic, while the company “maintained” the FY26 net income outlook rather than raising it. Ross Stores reported AMC at $2.02 versus the $1.70 consensus (an 18.8 percent beat), $6.01 billion revenue versus $5.64 billion consensus, and the FY26 EPS guide raised to a $7.50 to $7.74 range with the Q2 guide at $1.85 to $1.93, the cleanest off-price cohort print of the trade-down cycle. Ralph Lauren reported AMC at $2.80 EPS versus the $2.54 consensus, Q4 revenue at $1.98 billion (plus 17 percent year on year) versus the $1.85 billion consensus, and FY26 total revenue crossing $8 billion for the first time at $8.11 billion. Williams-Sonoma reported BMO at $1.93 EPS on $1.81 billion revenue with comparable brand revenue plus 4.8 percent, West Elm comp plus 8.5 percent, Pottery Barn plus 1 percent, Williams Sonoma flagship plus 5 percent, an operating margin of 16.2 percent, and $373 million returned to shareholders. NVDA closed Thursday cash at $219.45 versus the Wednesday after-hours mark at $220.64, a muted reaction to the Q1 FY27 blowout that prompted Baird’s Tristan Gerra to lift the price target to $500 from $300 while the broader desk read the cash-equity setup as positioned for the June 1 Computex Taipei keynote rather than the Q1 print itself. The S&P Global PMI Flash printed Thursday with Manufacturing at 55.3 (above the 53.8 consensus and the strongest expansion since May 2022), Services at 50.9 (below the 51.1 consensus and the weakest calendar quarter since late 2023), and Composite at 51.7, with input prices the highest since June 2022 on the manufacturing side and the highest in a year on the services side, the cleanest single confirmation that the Iran-war energy passthrough has now landed in the cost structure. UMich Consumer Sentiment Final for May releases at 10 AM ET with the preliminary read near the historic trough at 50.8 and year-ahead inflation expectations at 4.5 percent. Asia delivered a clean follow-through to Thursday’s blowout rally with the Nikkei closing plus 2.68 percent at 63,339 for the second consecutive monster session, Topix plus 1 percent at 3,892, Hang Seng plus 1.17 percent at 25,684 on the deal-optimism bid, and the Kospi consolidating plus 0.23 percent at 7,833 after Thursday’s plus 7.68 percent surge. Europe opened broadly higher with Stoxx 600 plus 0.6 percent, FTSE 100 plus 0.58 percent, DAX plus 0.65 percent, CAC 40 plus 0.57 percent, all four major bourses bid on the deal-optimism tape and the constructive US corporate read.
Three things to internalize before the open:
-
The Iran narrative is now structurally bifurcated between the constructive “narrowed gaps” rhetoric from the Araghchi-Munir mediation track and the unresolved binding constraints of uranium-stays-in-country plus the leaked Iran-Oman Hormuz toll framework that Trump has explicitly rejected. The right structural read is that the deal probability is rising toward a 45-50 percent base case for a Memorial-Day-weekend memo but the binding-constraint two-front gap (uranium plus Hormuz tolls) keeps the energy curve volatile inside a $98-108 Brent range through next week. Iran’s offer of a 12-year nuclear program suspension against the US demand for at least 20 years is the cleanest single concession-shape signal of the negotiation, and the parallel release of 20 Iranian sailors via the Pakistan channel is the goodwill confirmation that the back-channel is functioning. The Brent re-rate from the Thursday $102.58 close back to $105.29 on the toll framework leak is the structural confirmation that the front-month curve is now sensitive to single-headline binary risk in both directions, with the Memorial Day Weekend gas pump price binary running into the closed-market Monday session as the tactical hedge driver. We raise the memo probability mark to 46 percent from the Thursday 34 percent on the Araghchi “narrowed gaps” language and the Munir agenda confirmation, partially offset by the Khamenei uranium hold and the Hormuz toll leak. The right discipline is to hold the existing XLE structure (the 99/108 call spread re-added Thursday) and add a small Brent August 105/115 call spread protected by the short 95 put at 0.10 percent NAV gross on the open.
-
The Warsh swearing-in at the White House at 11 AM ET is symbolically the cleanest single political-Fed convergence signal in 40 years (last White House ceremony was Greenspan in 1987) and the institutional reads are that (a) the new chair starts with a hawkish four-vote internal block confirmed in Wednesday’s April minutes, (b) Powell staying on as Governor through January 2028 is a deliberate institutional buffer against unilateral political pressure, and (c) the curve has not yet repriced the dot-plot path into the June 16-17 first Warsh FOMC. The 10Y at 4.55 percent is three basis points off the Thursday print on the deal-optimism duration bid, but the structural read is that the dissent language (“some policy firming would likely become appropriate”) combined with the Warsh historic hawkish bias on the Federal Funds rate puts the December 2026 SOFR pricing setup vulnerable to a 25-50 basis point compression in the rate-cut path through the dot plot. We hold the SOFRZ6 96.25/96.00 put spread (Wednesday entry at 4.5 net debit) at the current 5.30 mark, locking in 18 percent of the structure premium, and hold the 30Y short via the TYZ pair at 5.07 yield, with the structural compounding into the June 16-17 print intact. The first Warsh public statement post-swearing-in is the binding short-term curve catalyst.
-
The Deere blowout plus the Ross Stores big beat plus the Ralph Lauren clean print plus the Williams-Sonoma solid comp are the cleanest single confirmation that the corporate cycle has not broken despite the consumer confidence trough at the UMich preliminary 50.8 print, and the structural read is that the cyclical-cohort positioning has bottomed and is now setting up for a Q3 multiple re-rate. Deere’s 12.7 percent EPS beat with the 16 percent jump in Small Ag and the 29 percent jump in Construction and Forestry is the cleanest single read that the ag cycle is bottoming on the OEM side, even with the company “maintaining” rather than raising the FY26 outlook. Ross Stores’ 18.8 percent EPS beat plus the FY guide raise to $7.50-$7.74 is the structural confirmation that the off-price cohort is fully capturing the trade-down dynamic that Walmart’s soft Q2 guide flagged Thursday morning, and the inverse-Walmart read is now binding. Ralph Lauren’s clean 17 percent revenue growth and the $8.11 billion FY breakthrough is the structural luxury-resilience read that the discretionary-high-end cohort is intact. We hold the IYT call spread, add a small DE June 19 540/570 call spread at 0.05 percent NAV gross on the open (DE closed Thursday at $522), trim the WMT long to zero, and add a small ROST June 19 175/185 call spread at 0.05 percent NAV gross.
What Posted Overnight
Iran: “Narrowed Gaps” Rhetoric + Hormuz Toll Twist (Thursday Eve to Friday AM)
| Item | Detail |
|---|---|
| Foreign Minister Araghchi line | US text “narrowed the gaps to some extent” |
| Iran’s nuclear ask | 12-year program suspension |
| US ask on suspension | At least 20 years |
| Khamenei uranium directive | Still in effect (60% enriched stays) |
| Iran-Oman Hormuz toll framework | Permanent fee mechanism, leaked overnight |
| Trump response on Hormuz | “Open, free, and without toll charges” |
| Pakistan-Munir Tehran outcome | “Finalizing an agenda” for direct talks next week |
| 20 Iranian sailors | Released via Pakistan mediation Thu |
| War day count | 84 |
| Memo probability (Fri mark) | 46% (up from 34% Thu) |
| Brent reaction | +2.7% to $105.29 (after -2.0% Thu close) |
Our take on the Iran setup: The “narrowed gaps” language from Araghchi is the cleanest single positive rhetoric since the Monday postponement framing, and the 12-year nuclear suspension offer versus the US 20-year ask is the cleanest single concession-shape we have seen on the negotiation track. The 20 sailors release is the goodwill confirmation that the Pakistan channel is operationally functional. Against that, the leaked Iran-Oman Hormuz toll framework is the structural read that Tehran is still positioning to monetize and formalize its control of the strait, which is the binding-constraint that Trump has explicitly rejected. The Khamenei uranium hold is the binding nuclear-side constraint that has not moved. We raise the memo probability mark to 46 percent on net, which is structurally bullish risk-on but materially below the 60 percent threshold for a clean deal-priced positioning. The Brent bounce to $105 is the tactical confirmation that the curve is now headline-sensitive in both directions, and we re-add a small Brent August call spread protected by the short put.
Deere Q2 FY26 (Thursday May 21 BMO)
| Metric | Consensus | Actual | Beat / Miss |
|---|---|---|---|
| EPS | $5.81 | $6.55 | Beat (+12.7%) |
| Worldwide Net Sales | $11.4B (rev only) | $13.37B (total) | +5% YoY |
| Net Income | $1.80B | $1.773B | Modest miss |
| Small Ag & Turf Sales | n/a | +16% YoY | Strong |
| Construction & Forestry | n/a | +29% YoY | Big |
| Small Ag Operating Margin | n/a | 20.6% | Solid |
| FY26 Outlook | n/a | Maintained | In line |
Our take on Deere: A clean 12.7 percent EPS beat with the standout 29 percent jump in Construction and Forestry and the 16 percent lift in Small Ag and Turf is the structural read that the OEM ag cycle has bottomed and the cyclical-cohort positioning is now setting up for a Q3 multiple re-rate. The “maintained” FY26 outlook rather than a raise is the cautious management discipline read on the Iran-war energy passthrough into fertilizer and diesel costs, but the segment-level acceleration is the binding positive. Read-across is bullish for AGCO, CNH Industrial, and modest positive for Caterpillar on the C&F translation. We add a small DE June 19 540/570 call spread at 0.05 percent NAV.
Ross Stores Q1 2026 (Thursday May 21 AMC)
| Metric | Consensus | Actual | Beat / Miss |
|---|---|---|---|
| EPS | $1.70 | $2.02 | Beat (+18.8%) |
| Revenue | $5.64B | $6.01B | Beat (+6.6%) |
| FY26 EPS Guide | n/a | $7.50-$7.74 | Raised |
| Q2 2026 EPS Guide | $1.79 | $1.85-$1.93 | Above consensus |
Our take on Ross Stores: The 18.8 percent EPS beat plus the FY guide raise to a $7.50-$7.74 range plus the Q2 guide above consensus is the cleanest single off-price cohort print of the year, and the structural read is that the trade-down dynamic from Walmart’s soft Q2 guide Thursday morning is fully flowing into the off-price flywheel. The inverse-Walmart read is now binding, and the Target outperformance Tuesday confirms the higher-income trade-down rotation. We add a small ROST June 19 175/185 call spread at 0.05 percent NAV.
Ralph Lauren Q4 FY26 (Thursday May 21 AMC) + Williams-Sonoma Q1 (Thu BMO)
| Company | EPS Beat | Revenue Beat | Key Detail |
|---|---|---|---|
| RL | $2.80 vs $2.54 | $1.98B vs $1.85B (+17% YoY) | FY first time over $8B at $8.11B |
| WSM | $1.93 EPS | $1.81B rev, +4.8% comp | West Elm +8.5%, $373M returned |
Our take on the discretionary cohort: The luxury-resilience read from Ralph Lauren’s 17 percent revenue growth and the $8 billion FY breakthrough is the cleanest single confirmation that the high-end discretionary cohort is intact despite the consumer-confidence trough. Williams-Sonoma’s plus 4.8 percent comp with West Elm leading at plus 8.5 percent is the structural read that the home furnishings cohort has stabilized after two years of decline. We do not add to the luxury cohort but hold the existing RL exposure and trim into year-end strength.
Asia and Europe Friday Cash
| Market | Close / Mark | Change | Note |
|---|---|---|---|
| Nikkei 225 | 63,339 | +2.68% | Second monster session; SoftBank consolidating |
| Topix | 3,892 | +1.00% | Banks bid, tech holds |
| Kospi | 7,833 | +0.23% | Consolidating Thu’s +7.68% rip |
| Hang Seng | 25,684 | +1.17% | Deal-optimism bid |
| Shanghai CSI 300 | 4,835 | +0.35% | Property cohort lift |
| Stoxx 600 | 617 | +0.60% | Fourth consecutive up day |
| FTSE 100 | 10,295 | +0.58% | Energy plus deal-optimism bid |
| DAX | — | +0.65% | Autos lift, industrials follow |
| CAC 40 | 7,960 | +0.57% | Luxury cohort bid (RL read-across) |
Asia is structurally cleaner than Europe in absolute terms with the Nikkei consolidating Thursday’s blowout (+2.68 percent for a second consecutive monster session) and the Hang Seng catching up plus 1.17 percent on the deal-optimism read after lagging Thursday. The Kospi held the bulk of Thursday’s plus 7.68 percent surge with a modest plus 0.23 percent consolidation, which is the binding confirmation that the semi-cohort positioning is now sticky rather than mean-reverting. Europe lifted broadly with all four major bourses up between 0.57 and 0.70 percent on the constructive US corporate read plus the Iran de-escalation rhetoric, on track for the Stoxx 600 weekly gain at 2.25 percent.
Key Events Today and Through Next Week
| Date | Time (ET) | Event | Consensus / Note |
|---|---|---|---|
| Fri May 22 | 7:00 | Williams-Sonoma (WSM) BMO | Printed: $1.93 EPS, +4.8% comp |
| Fri May 22 | 10:00 | UMich Sentiment Final (May) | Prelim 50.8, inflation exp 4.5% |
| Fri May 22 | 11:00 | Warsh White House Swearing-In | First WH ceremony in 40 years |
| Fri May 22 | All day | Pakistan-Munir-Tehran follow-up | Agenda finalization |
| Fri May 22 | All day | Memorial Day Weekend setup | Gas pump price binary |
| Mon May 25 | — | US Markets Closed (Memorial Day) | Bond market closed |
| Tue May 26 | AMC | Palo Alto Networks (PANW) | $0.78 EPS / $2.28B rev cons |
| Wed May 27 | AMC | NVIDIA (PANW peers), CrowdStrike | Read-across watch |
| Wed May 27 | AMC | Snowflake (SNOW) Q1 FY27 | $0.32 EPS / $1.32B rev cons |
| Thu May 28 | 8:30 | Durable Goods (April) | -1.5% m/m cons |
| Thu May 28 | 8:30 | Initial Jobless Claims | 210K cons |
| Fri May 30 | 8:30 | Core PCE (April) | 2.8% YoY cons |
| Sun May 31 | 8 PM PT | NVDA Computex Taipei keynote | N1 GPU, Rubin cadence |
| Sat Jun 7 | All day | OPEC+ Ministerial (Vienna) | Production response |
| Tue Jun 16-17 | 2 PM | Warsh first FOMC + Dot Plot | Hawkish 4-vote block |
Warsh Swearing-In at 11 AM ET | Institutional Reads
Kevin Warsh’s 11 AM ET swearing-in at the White House is the cleanest single political-Fed convergence signal of the post-Volcker era, with the last White House ceremony for a new Fed Chair being Alan Greenspan in 1987 (38 years ago). The institutional reads are threefold. First, Warsh inherits a hawkish four-vote internal block confirmed in Wednesday’s April minutes (Hammack, Kashkari, Logan formal dissents plus Schmid and Bowman non-voter pushbacks against the easing bias), which structurally prevents any dovish pivot in the June 16-17 dot plot regardless of Warsh’s preferred glide path. Second, Powell’s decision to stay on as Governor through January 2028 is the deliberate institutional buffer against any unilateral political pressure on the rate path, with Powell retaining a vote on the FOMC alongside the regional Fed presidents. Third, Warsh has historically expressed a markedly more hawkish bias on the natural rate of interest and on the path of inflation expectations than the consensus FOMC line, which combined with the dissent-confirmed institutional positioning sets up the December 2026 SOFR curve for a 25-50 basis point compression in the priced rate-cut path. We hold the SOFRZ6 96.25/96.00 put spread at the current 5.30 mark (entry 4.5 Wednesday, 18 percent of structure premium captured) and hold the 30Y short via the TYZ pair at 5.07 yield. The first Warsh public statement post-swearing-in is the binding short-term curve catalyst, and the June 16-17 first Warsh FOMC plus dot plot is the binding medium-term catalyst.
Iran Mediation Track and the Memorial Day Weekend Binary
The Pakistan-mediated track via Army Chief Munir’s Thursday Tehran visit concluded with mediators “finalizing an agenda” rather than a deal text, with direct US-Iran negotiations expected to resume as early as next week. The Araghchi line that the US text “narrowed the gaps to some extent” plus the parallel release of 20 Iranian sailors via the Pakistan channel are the goodwill confirmations that the back-channel is fully operational. Against that, the leaked Iran-Oman Hormuz toll framework overnight (a formalization of Tehran’s control of strait traffic via a permanent fee mechanism) is the binding-constraint that Trump has explicitly rejected, and the Khamenei uranium-stays-in-country directive from Wednesday evening remains in effect with no walkback. The 12-year nuclear suspension offer against the US 20-year demand is the cleanest single concession-shape we have seen, but the eight-year delta is structurally larger than any prior bilateral negotiating gap in the JCPOA history. We raise the memo probability mark to 46 percent (from 34 percent Thursday) on the constructive rhetoric, but the binding two-front gap (uranium plus Hormuz tolls) keeps the energy curve sensitive to single-headline binary risk in both directions. The Memorial Day Weekend gas pump price binary is the tactical hedge driver running into Monday’s closed-market session, and the right discipline is to add a small Brent August call spread protected by the short put.
Trade Ideas | Sized for the Iran Headline Risk and the Warsh Transition
Brent August 105/115 Call Spread + Short 95 Put + Hold XLE June 19 99/108 (New + Hold)
Open new on the Hormuz toll twist and the structural-tail two-front gap: open the Brent August 105/115 call spread at the 4.10 net debit on the open, finance partially by the short 95 put at 0.85 credit, for a net 3.25 debit per spread structure at 0.10 percent NAV gross sized. Hold the XLE June 19 99/108 call spread at 0.20 percent NAV (Thursday re-add at 4.80 net debit, currently marked 5.10 on the bounce). The structure expresses the read that the binding-constraint two-front gap (uranium-stays plus Iran-Oman Hormuz toll framework) keeps the Brent curve volatile inside a $98-108 range through next week, with the Memorial Day Weekend gas pump binary the tactical hedge driver and the OPEC+ Ministerial June 7 the binding production-side catalyst. PT 8.50 on the Brent structure (top of $115 strike), PT 7.50 on the XLE structure. Stop on a clean Memorial Day Weekend memo announcement with both Hormuz tolls dropped and uranium-shipment agreed at 50 percent. Risk: a Munir-mediated breakthrough Monday or Tuesday with a partial uranium shipment plus a Hormuz toll-drop concession would re-rate the Brent curve $8 lower and the XLE structure would expire near zero; the combined 0.30 percent NAV sizing plus the short 95 put protection is calibrated to be losable on the deep deal-close scenario. The short 95 put is the protective hedge against the deal-close downside.
SOFRZ6 96.25/96.00 Put Spread + 30Y TYZ Short + Hold (Roll Strikes if 96.20)
Hold the SOFRZ6 96.25/96.00 put spread (Wednesday entry at 4.5 net debit, 0.05 percent NAV) at the current 5.30 mark, locking in 18 percent of the structure premium versus the Thursday 5.10 mark on the deal-optimism duration bid; roll the strikes lower (96.00/95.75) only if SOFRZ6 closes below 96.20 today on the Warsh swearing-in and the UMich print. Hold the 30Y short via the TYZ pair at 5.07 yield (three basis points off the Thursday print on the deal bid). The structure expresses the read that the Warsh inheritance of a hawkish four-vote internal block plus Warsh’s historic hawkish bias on the natural rate plus the staff-projection 2026 core PCE upward revision will compress the December 2026 SOFR rate-cut path from the current ~87 basis points priced to a 50-65 basis point range. PT 7.00 on the SOFR structure; stop on a 96.50 SOFRZ6 close on a dovish Warsh first-public-statement framing. Risk: a dovish Warsh first signal in his swearing-in remarks plus a clean Iran deal Monday would compress the curve toward a 96.40 SOFRZ6 and expire the structure near zero; the 0.05 percent NAV sizing is calibrated to be losable on the dovish-tail. The TYZ 30Y short structurally compounds on the hawkish-dot-plot read into June 16-17.
Cyclical Cohort Pair: DE 540/570 Call Spread + ROST 175/185 Call Spread (New)
Open new the Deere June 19 540/570 call spread at the 8.20 net debit on the open (DE closed Thursday at $522, the structure captures roughly 4 percent upside above strike) and the Ross Stores June 19 175/185 call spread at the 3.40 net debit (ROST closed at $169, the structure captures roughly 4 percent upside above strike), each sized at 0.05 percent NAV gross. The pair expresses the read that the Deere blowout 12.7 percent EPS beat plus the 29 percent C&F segment lift confirms the ag-OEM cycle bottoming plus the inverse-Walmart trade-down dynamic that Ross Stores’ 18.8 percent EPS beat plus the FY guide raise has fully captured. Combined PT 16.00 on the DE structure, 7.50 on the ROST structure. Stop on a single-stock disappointment headline (DE downward revision to FY26 outlook in the Q2 FY26 update mid-cycle, or a ROST consumer-confidence linkage in the next macro print). Risk: a clean consumer-confidence trough re-rate on the UMich Final at 10 AM ET below 50.0 plus a hot UMich inflation expectation above 4.7 percent would compress both legs on a stagflation re-read; the combined 0.10 percent NAV sizing is calibrated to be losable on the stagflation-tail.
Signal Tracker | Friday 8:30 AM ET Mark
The Friday mosaic is structurally constructive but binary-bifurcated, with the cleanest single Iran de-escalation rhetoric of the week (“narrowed gaps” plus 12-year nuclear suspension offer plus 20 sailors released) running into the binding two-front gap (Khamenei uranium hold plus leaked Iran-Oman Hormuz toll framework) that Trump has explicitly rejected, against a backdrop of the Warsh 11 AM ET White House swearing-in (first since Greenspan 1987), the cleanest single corporate-cycle confirmation of the cycle (Deere plus 12.7 percent EPS beat, Ross Stores plus 18.8 percent, Ralph Lauren plus 10.2 percent, Williams-Sonoma plus 4.8 percent comp), and a duration-bid tape (10Y at 4.55 minus three basis points, 30Y at 5.07 minus three) that has yet to reprice the hawkish dot-plot trajectory into June 16-17. The bullish risk-on count is 16 (up from 14 Thursday on the Araghchi narrowed-gaps line plus the Deere/ROST/RL prints), the bearish count is nine (down from 11 Thursday but with the structural Hormuz toll and uranium overhang intact), and the neutral count is four. Energy is bid back $3 higher on the toll twist (Brent $105, WTI $98), Asia delivered a follow-through to Thursday’s monster session with the Nikkei plus 2.68 percent (second consecutive plus 2 percent close) and Hang Seng plus 1.17 percent, Europe is up broadly between 0.57 and 0.70 percent on the deal-optimism plus US corporate read, and vol is structurally low with the VIX at 16.76 (below 17 for the first time since the Iran war started). The book is now positioned at plus 5.6 percent net long gross (up from plus 5.4 percent Thursday on the Deere and ROST adds plus the Brent August add) on the SMH and SK Hynix long hold, the XLE plus new Brent structure, the SOFRZ6 put spread plus 30Y short hold, the new DE and ROST call spreads, and the trimmed WMT plus held TGT exposures. The Memorial Day Weekend gas pump binary into the Monday closed session is the tactical hedge driver, and the binding catalysts into next week are the Warsh first public statement post-swearing-in, the resumed US-Iran direct talks, the May 30 Core PCE print, the June 1 Computex Taipei keynote, and the June 7 OPEC+ Ministerial running into the June 16-17 first Warsh FOMC.
What Could Be Wrong
The Friday mark is a structurally constructive read on the Iran de-escalation rhetoric, a structurally bearish-tail read on the Hormuz-toll plus uranium two-front gap, a structurally bullish read on the cyclical-cohort corporate cycle, and a structurally bearish read on US duration into the Warsh transition. The three biggest sources of error in this setup are:
-
A clean Memorial Day Weekend memo announcement on Sunday or Monday with both Hormuz tolls dropped and a 30-50 percent uranium shipment agreed as the compromise framework. The asymmetry is real because the Araghchi “narrowed gaps” language plus the 20 sailors release plus the Munir agenda finalization are all goodwill signals that the back-channel is operationally functional, and the eight-year suspension delta (12 vs 20) is bridgeable through a phased monitoring framework. We model the probability of a Memorial Day Weekend memo at 28 percent, the structural-hardening continuation at 22 percent, and the status-quo no-decision through next week at 50 percent. The right play is to hold the Brent August call spread protected by the short 95 put rather than press the long energy structure into the weekend.
-
A clean UMich Final at 10 AM ET below 50.0 with year-ahead inflation expectations above 4.7 percent that confirms the stagflation re-read on the cyclical cohort. The preliminary print at 50.8 plus the 4.5 percent inflation expectations is the structural read that the consumer-confidence trough is now embedded, and any further deterioration would compress the cyclical-cohort positioning we are adding into (DE 540/570 call spread, ROST 175/185 call spread). We model the probability of a UMich final below 50.0 at 25 percent and the inflation expectations above 4.7 percent at 30 percent. The 0.10 percent combined NAV sizing on the cyclical cohort adds is calibrated to be losable on the stagflation-tail.
-
A dovish Warsh first public statement in his swearing-in remarks that breaks the hawkish institutional expectation and compresses the duration short positioning. Warsh has historically expressed a hawkish bias on the natural rate and on inflation expectations, but a first-public-statement pivot toward a “data-dependent” or “preserving optionality” framing would be the structural read that the new chair is positioning to retain dovish flexibility into the June dot plot. We model the probability of a dovish Warsh first signal at 15 percent and the structural-hawkish framing at 60 percent. The 0.05 percent NAV sizing on the SOFRZ6 put spread is calibrated to be losable on the dovish-tail, and the 30Y short structurally compounds on the hawkish-dot-plot read into June 16-17.
The book is not betting on any single catalyst into the long weekend; it is positioned for the dispersion across the next 72 hours (Warsh swearing-in 11 AM ET, UMich Final 10 AM ET, Iran headline risk through Sunday, Memorial Day closed Monday) to widen on either deal-close or deal-stall direction, with the Brent August protective structure plus the SOFRZ6 short plus the cyclical-cohort adds positioned to harvest the dispersion rather than press the directional view.
This note reflects information available as of May 22, 2026, 8:30 AM ET, one hour before the cash open and following the Araghchi “narrowed gaps” rhetoric Thursday evening, the leaked Iran-Oman Hormuz toll framework overnight, the Deere/Ross Stores/Ralph Lauren earnings prints, the S&P Global PMI Flash Thursday morning, and ahead of the 10 AM UMich Final Sentiment plus the 11 AM Warsh White House swearing-in. Markets open at 9:30 AM ET and close at 1:00 PM ET ahead of Memorial Day; US markets are closed Monday May 25. The Trump Truth Social cadence through the long weekend and any leak on the resumed US-Iran direct talks may reset positioning by next Tuesday’s reopen. The May 30 Core PCE print, the June 1 Computex Taipei keynote, the June 7 OPEC+ ministerial, and the June 16-17 first Warsh FOMC plus dot plot are the binding catalysts into mid-month. For internal use only. Not investment advice.