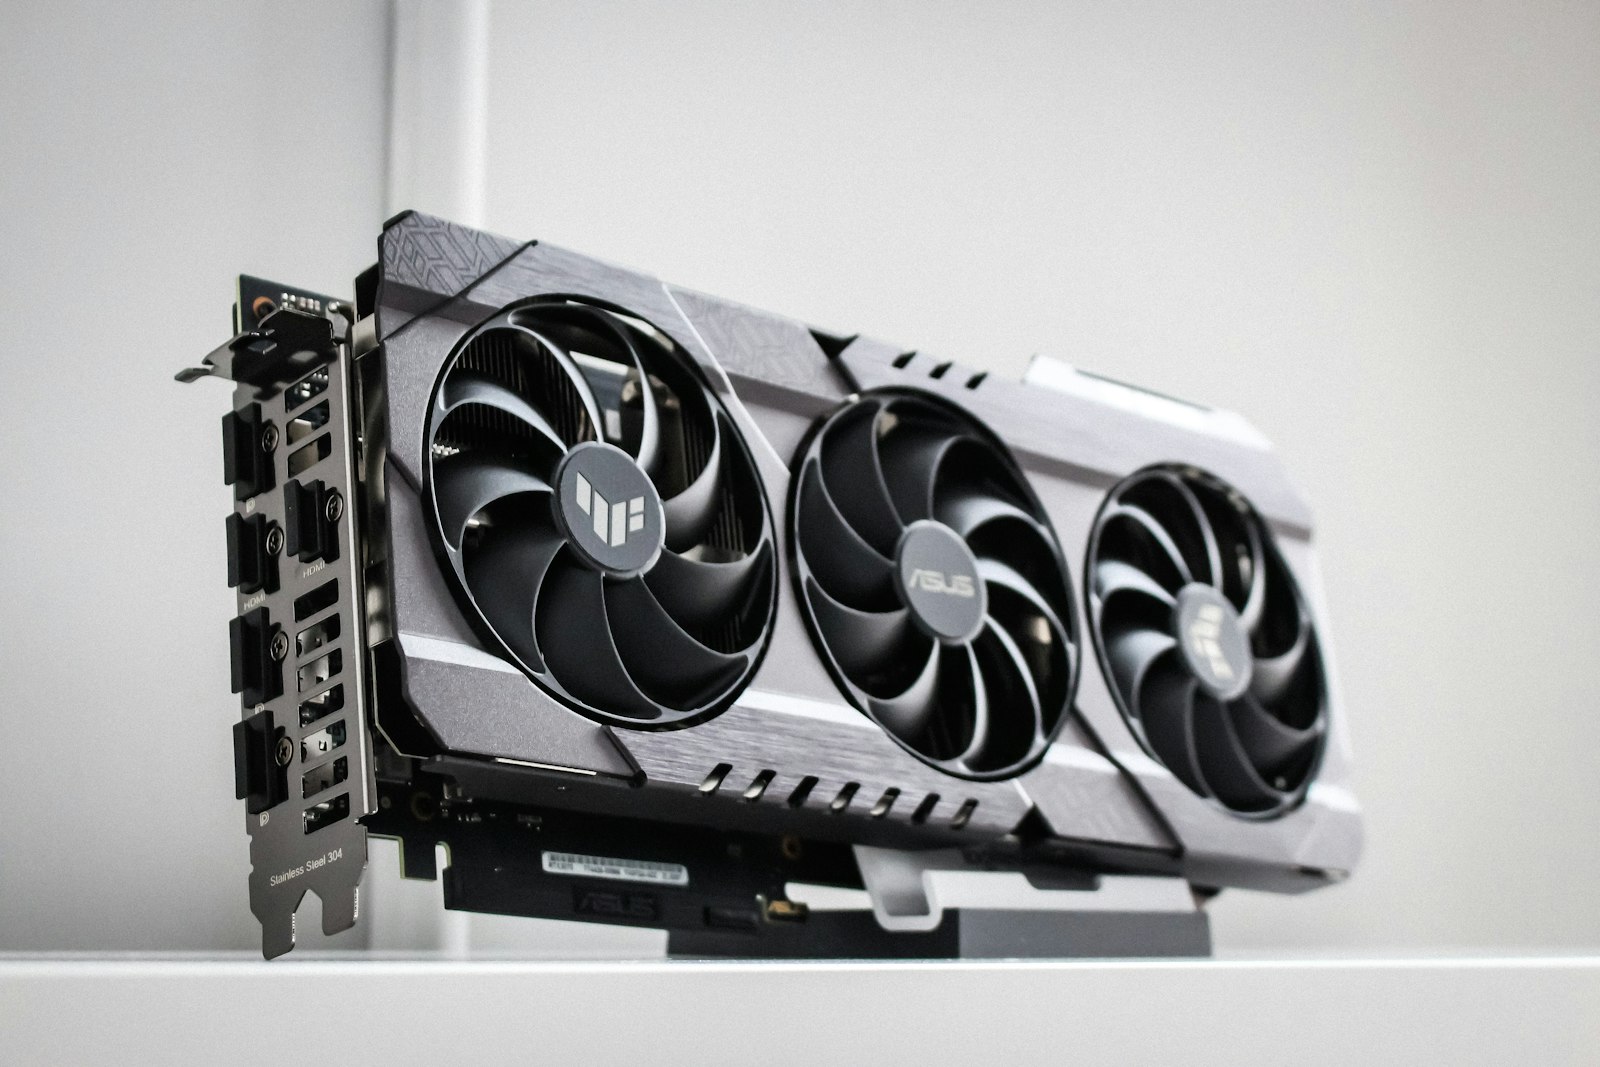
Monday pre-market, 7:00 AM ET. Nvidia CEO Jensen Huang took the stage at Computex 2026 in Taipei overnight and delivered what amounts to the most significant PC platform shift in four decades. The RTX Spark superchip pairs a custom Arm-based N1X CPU (designed with MediaTek) with a Blackwell GPU packing 6,144 CUDA cores and up to 128 GB of unified LPDDR5X memory, delivering 1 petaflop of AI performance in a laptop form factor. Huang called it “the first completely re-engineered, reinvented line of PCs that has happened in 40 years.” Launch partners include Microsoft, Dell, HP, ASUS, Lenovo, and MSI, with the Surface Laptop Ultra, Dell XPS 16, and HP OmniBook Ultra 16 shipping this fall. Intel fell 6.5% and AMD dropped 4.2% in pre-market trading as Nvidia’s entry into the CPU market directly threatens their decades-long PC duopoly. Microsoft rose nearly 4%, Arm gained 3%, and Nvidia itself climbed 2%.
Alongside the PC announcement, Huang confirmed that the Vera Rubin platform is now in full production. Six new chips in the Rubin family promise up to a 10x reduction in inference token cost versus Blackwell. The Nemotron 3 Ultra, a roughly 500-to-550 billion parameter reasoning model, was also unveiled alongside a DGX Station for Windows aimed at developers. Nvidia separately announced a multiyear strategic partnership with Meta spanning on-premises, cloud, and AI infrastructure, and disclosed an investment and technology partnership with Anthropic.
On the geopolitical front, the US-Iran 60-day Hormuz memorandum remains unsigned heading into the new week. Trump said in a weekend Fox News interview that a deal has not been finalized and that he is pressing for terms that guarantee Iran never acquires a nuclear weapon. US and Iranian forces exchanged strikes over the weekend, pushing Brent crude back up to $93.37 (up 2.2%) after Friday’s dip to six-week lows at $91.37. The Strait of Hormuz has been effectively closed since March 4, with Iran continuing to threaten ships and maintaining deployed mines. The gap between diplomatic language and ground-level escalation remains the core risk for energy markets. Separately, on the Russia-Ukraine track, the aftermath of last week’s Russian drone strike on a NATO member (Romania) continues to reverberate, with Bucharest pressing NATO for accelerated anti-drone capabilities and the alliance reaffirming its territorial defense posture.
Futures opened modestly higher to start June. S&P 500 futures are up 0.16% at 7,593, Dow futures up 0.27% at 51,172, and Nasdaq futures up 0.13% at 27,013. The Russell 2000 is the odd one out, down 0.21%, as small caps continue to lag the large-cap record-setting streak. The VIX ticked up 3.3% to 15.82 from Friday’s 15.32 close, reflecting the weekend geopolitical noise. Gold fell 1.3% to $4,538, giving back some of the deal-uncertainty safe-haven bid as risk appetite holds. Bitcoin dropped 1.95% to $72,355, extending its May correction. The 10-year Treasury yield edged up 1 basis point to 4.45%, largely stable after Friday’s two-week-low print on the cool Core PCE read.
Asia closed strong: the Nikkei 225 surged 0.91% to a record 66,934, led by SoftBank (+14%), Kioxia (+10.1%), and Murata Manufacturing (+9%) on the Computex AI chip enthusiasm. The Hang Seng gained 0.86% while the CSI 300 fell 0.98% to 4,844 on continued mainland profit-taking. European markets opened higher with the Stoxx 600 up 0.57% to 624 and the DAX rising 0.77% to 24,796. Goldman Sachs raised its Stoxx 600 12-month target to 660.
In notable pre-market movers beyond the chip names: IBM surged 13% after Barclays initiated coverage with an overweight rating on a thesis that quantum computing is the next major compute paradigm and IBM’s strategy is the most compelling in the space. Software names are extending their rally, with the iShares Expanded Tech-Software Sector ETF (IGV) up 4.5% in pre-market.
Key Data and Events Today
| Time (ET) | Event | Expectation | Note |
|---|---|---|---|
| 9:45 AM | S&P Global US Mfg PMI Final (May) | – | Watch |
| 10:00 AM | ISM Manufacturing (May) | 52.6 | Watch vs Chicago PMI 62.7 signal |
| All Day | Computex 2026 continues (Taipei) | – | GTC Taipei Jun 1-5 |
| – | Israel-Lebanon talks (Washington) | – | Day 1 of two-day round |
Key Events This Week
| Date | Time (ET) | Event | Note |
|---|---|---|---|
| Tue Jun 3 | AMC | Broadcom (AVGO) Q2 FY26 | $2.32 EPS / $22B rev / AI rev $10.7B cons |
| Tue Jun 3 | AMC | CrowdStrike (CRWD) Q1 FY27 | $1.07 EPS / $1.36B rev |
| Tue Jun 3 | All Day | South Korea local elections | DPK favored, Seoul tight race |
| Wed Jun 4 | 8:15 AM | ADP Employment (May) | 175K consensus |
| Wed Jun 4 | 10:00 AM | ISM Services (May) | Watch |
| Fri Jun 6 | 8:30 AM | May Nonfarm Payrolls | 165K cons / U-rate 4.2 |
| Sat Jun 7 | All Day | OPEC+ Ministerial (Vienna) | Production decision, 3.24 mb/d cuts in place |
| Jun 16-17 | 2:00 PM | First Warsh FOMC + Dot Plot | 98% prob hold |
Nvidia Computex 2026 Key Announcements
| Announcement | Detail | Market Impact |
|---|---|---|
| RTX Spark / N1X | Arm CPU + Blackwell GPU, 128 GB unified, 1 PFLOP AI | NVDA +2%, INTC -6.5%, AMD -4.2% |
| Vera Rubin Production | 6 new chips, 10x inference cost reduction vs Blackwell | Accelerates AI capex cycle |
| Nemotron 3 Ultra | 500-550B param reasoning model | Competes with frontier LLMs |
| Meta Partnership | Multiyear, multigenerational GPU + networking deal | Validates hyperscaler demand |
| Anthropic Partnership | Investment + deep technology collaboration | Expands AI ecosystem reach |
| DGX Station for Windows | Developer-focused, brings DGX to Windows ecosystem | Broadens developer TAM |
Pre-Market Movers
| Ticker | Move | Catalyst |
|---|---|---|
| NVDA | +2% | RTX Spark unveil, Computex keynote |
| MSFT | +4% | RTX Spark co-development partner |
| ARM | +3% | N1X uses Arm architecture |
| IBM | +13% | Barclays OW initiation on quantum thesis |
| INTC | -6.5% | NVDA entering PC CPU market |
| AMD | -4.2% | NVDA entering PC CPU market |
| QCOM | -3% | NVDA competing in Arm PC space |
| IGV | +4.5% | Broad software rally into June |
Geopolitical Tracker
US-Iran: The 60-day Hormuz memorandum of understanding remains unsigned. Trump said over the weekend that a deal has not been finalized and he is pushing for terms that prevent Iran from ever acquiring a nuclear weapon. US and Iranian forces exchanged strikes over the weekend, pushing Brent back above $93 after dipping to $91.37 on Friday. The Strait has been effectively closed since March 4. Two sticking points persist: the Iranian enriched uranium stockpile reduction and Iran’s preference for a Hormuz transit service fee. The June 7 OPEC+ Ministerial in Vienna is the next inflection point for the production response to any deal.
Russia-Ukraine / NATO: The aftermath of the Russian drone strike on Galati, Romania continues to drive NATO security discussions. Romania expelled the Russian consul in Constanta, closed the consulate, and is pressing for accelerated anti-drone defense deliveries. NATO Secretary General Rutte reaffirmed territorial defense commitments. The drone incident is the first time a Russian strike weapon has hit a populated area in a NATO member state during the Ukraine war.
Israel-Lebanon: Fourth round of US-hosted talks begin today (June 2-3) in Washington. The 45-day ceasefire extension agreed on May 15 holds, though Israeli air strikes continue outside the terms of the truce. Key issues remain: IDF withdrawal from southern Lebanon and Hezbollah disarmament. Netanyahu has signaled a permanent IDF presence north of the Litani River.
South Korea: Local elections on June 3. The Democratic Party of Korea is favored broadly, with President Lee Jae-myung’s approval near 60%. The Seoul mayoral race is tight (Chong Won-o DPK 40% vs Oh Se-hoon PPP 37%).
This note reflects information available as of June 1, 2026, 7:00 AM ET. S&P 500 futures are at 7,593 (+0.16%), Dow futures at 51,172 (+0.27%), and Nasdaq futures at 27,013 (+0.13%). Nvidia CEO Jensen Huang unveiled the RTX Spark superchip at Computex 2026, entering the PC processor market for the first time. Intel fell 6.5% and AMD dropped 4.2% in pre-market on the competitive threat. The US-Iran 60-day Hormuz deal remains unsigned with weekend strikes pushing Brent back to $93.37. ISM Manufacturing for May is due at 10:00 AM (52.6 consensus). Broadcom and CrowdStrike report Tuesday after the close. The binding catalyst path runs through the ISM print today, the AVGO/CRWD prints Tuesday, the May NFP Friday, the OPEC+ Ministerial Saturday, and the first Warsh FOMC June 16-17. For internal use only. Not investment advice.