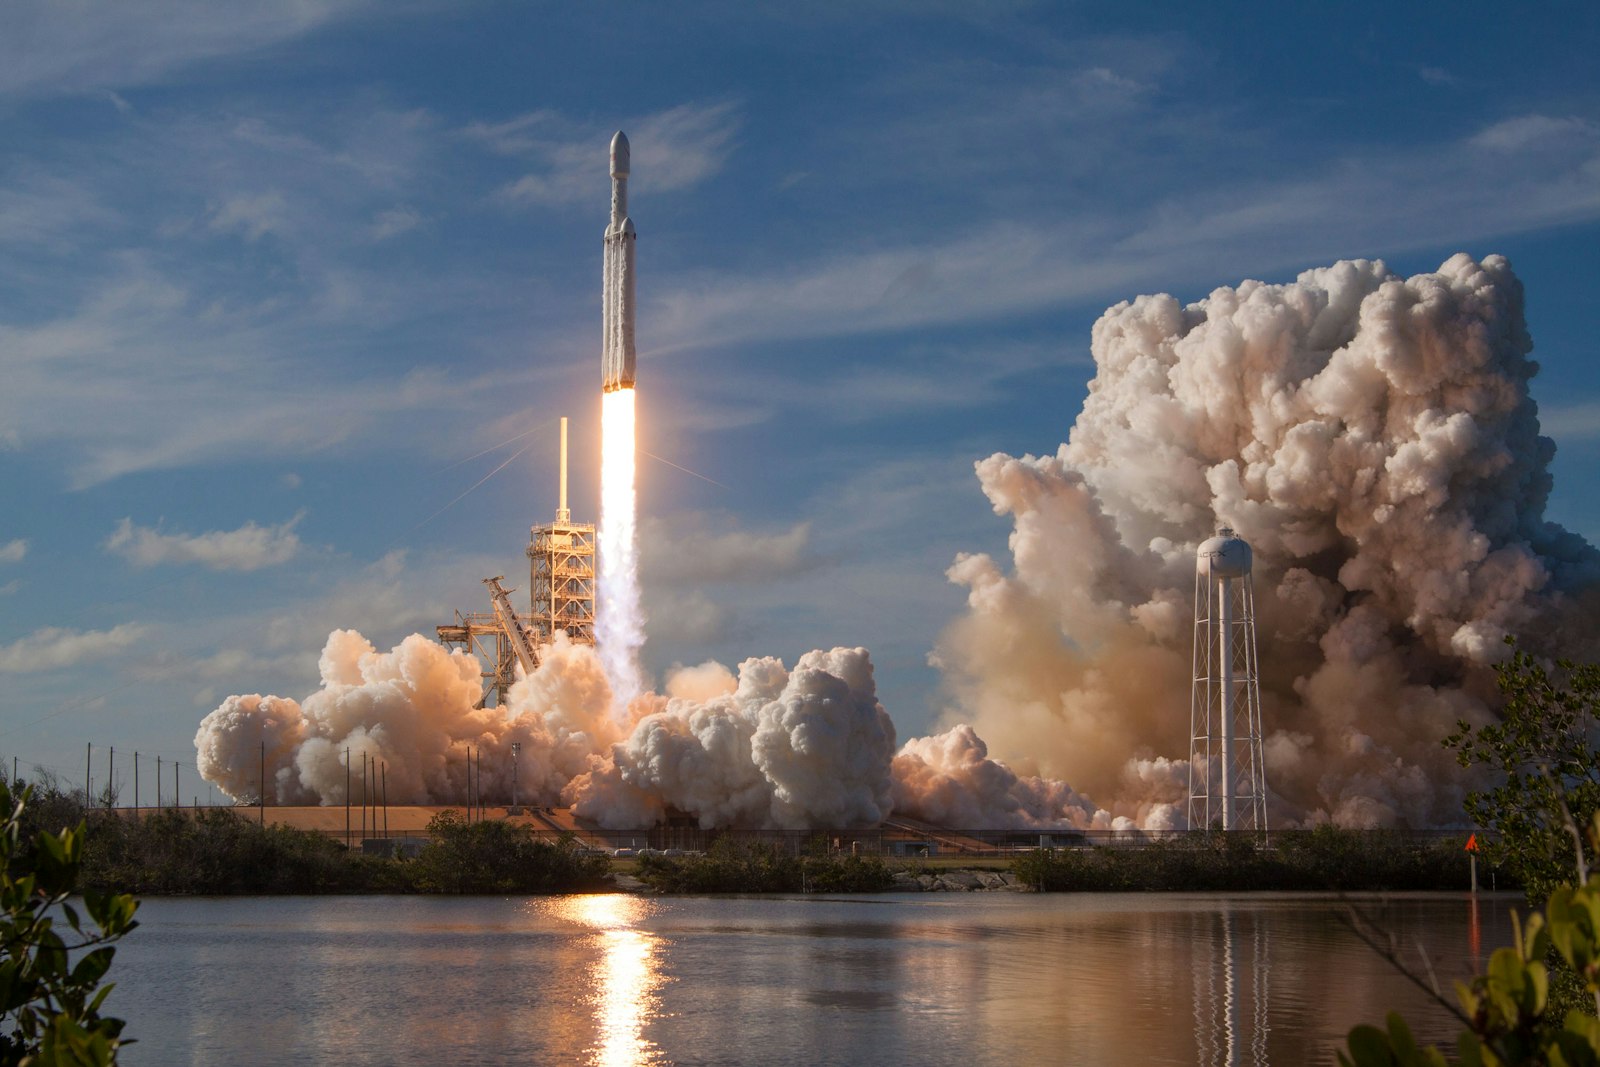
Friday pre-open, 7:30 AM ET. Today is dominated by one historic event: SpaceX begins trading on Nasdaq under ticker SPCX at $135 per share, the largest IPO ever at a $1.77 trillion valuation, making it instantly the seventh-largest US company, above Tesla. Alongside the debut, Trump’s claim of a framework peace deal with Iran is hammering oil, with Brent down nearly 4% to $88 and WTI at $84. That combination of reduced geopolitical risk premium and a landmark capital markets event is creating a rare setup where commodity bears and equity bulls can coexist. Futures are mixed, with the Dow up 0.34% and S&P 500 up 0.12% while Nasdaq lags at -0.18%, reflecting the Oracle post-earnings drag and Adobe’s after-hours drop pulling on mega-cap tech. Under the surface, the semiconductor complex continues its recovery with SanDisk up 14.5% and KLA up 12.9%. Gold is rebounding to $4,216 after hitting its November 2025 low yesterday, and Treasury yields are falling, with the 10-year dropping 7 basis points to 4.47% as the market re-prices geopolitical risk lower.
SpaceX IPO: The Biggest Debut in Market History
SpaceX begins trading today at $135 per share after raising $75 billion in what amounts to the largest initial public offering ever, more than triple Alibaba’s previous record. The company’s market cap at offering sits near $1.77 trillion, placing it above Tesla and just below Amazon. Shadow market pricing before the debut was pointing to a 35%+ spike at the open, though the fixed-price structure Elon Musk chose over a traditional bookbuild range makes the first-trade dynamics harder to predict. Retail allocation at 30% is unprecedented for a deal this size and reflects a deliberate strategy to build a broad shareholder base rather than concentrating ownership in institutional hands.
The read-through is significant across multiple sectors. SpaceX’s revenue mix covers launch services (Falcon 9, Starship), Starlink broadband, and defense contracts, making it a pure-play space and satellite name that fills a gap in public equity markets. For index funds, SPCX will need to be absorbed into Nasdaq and eventually S&P 500 inclusion, which means forced buying over the coming months. For Tesla, the picture is more nuanced. Both companies carry the Musk premium, but SpaceX now gives investors a direct way to own the infrastructure side of that story without the EV cycle risk.
Iran Peace Deal Framework Sends Oil Plunging
Oil prices are in freefall Friday morning after Trump declared the US had reached a “great settlement of the war with Iran” and Iranian state media reported a proposed 14-point peace document. The draft reportedly includes Iran reopening the Strait of Hormuz within 30 days in exchange for lifted oil sanctions, US military withdrawal, and up to $300 billion in reconstruction commitments from the US and allies. WTI fell 3.8% to $84.35 and Brent dropped 3.6% to $88.80, both touching two-month lows.
The key caveat is that Tehran pushed back through the Fars news agency, saying Iran has not approved any draft text for an initial memorandum of understanding with Washington. This is likely negotiating posture rather than a deal-breaker, as both sides have incentives to reach agreement, but the gap between “framework proposed” and “deal signed” remains significant. If the deal collapses over the weekend, oil reverses hard. If the Strait reopens on a 30-day timeline, over 12 million barrels per day of transit capacity returns to the market, and Brent heads toward $70s.
Adobe Q2: Beats and Raises, but Freemium Pivot Rattles Investors
Adobe reported record Q2 fiscal 2026 revenue of $6.62 billion, up 13% year-over-year, with non-GAAP EPS of $5.96 beating the $5.94 consensus. The company raised full-year revenue and earnings guidance, and AI-first ARR tripled year-over-year to over $500 million. On the surface, this is a clean beat-and-raise quarter. But shares fell 6.3% after-hours because management outlined an expanded freemium strategy that investors interpreted as a near-term headwind to annualized recurring revenue growth.
| Metric | Consensus | Actual | Beat/Miss |
|---|---|---|---|
| Revenue | $6.58B | $6.62B (+13% YoY) | Beat |
| Non-GAAP EPS | $5.94 | $5.96 | Beat |
| AI ARR | – | >$500M (3x YoY) | Strong |
| FY Guidance | – | Raised | Positive |
The freemium concern is worth watching but likely overblown. Adobe is following the same playbook that worked for Spotify, Canva, and Figma: widen the funnel, convert at scale. Near-term ARR compression is the cost of long-term TAM expansion. The AI ARR tripling to $500 million shows Firefly and generative tools are gaining traction, and that revenue stream barely existed 18 months ago.
Semiconductor Rally Broadens: SanDisk, KLA Lead
The chip recovery that started mid-week is accelerating. SanDisk surged 14.5% on strong flash memory demand projections, with Morgan Stanley raising its price target to $1,750 from $1,100 and citing a prolonged global memory upcycle where DRAM and NAND remain supply-constrained while AI demand ramps. KLA jumped 12.9% on a confluence of its 10-for-1 stock split payable date, analyst upgrades from Barclays and Cantor Fitzgerald (new PT $2,500), and revised industry spending estimates that now project $209.5 billion in global wafer fabrication equipment spending by 2027.
| Ticker | Move | Catalyst |
|---|---|---|
| SNDK | +14.5% | Memory upcycle, MS PT raise to $1,750 |
| KLAC | +12.9% | 10:1 split, Barclays/Cantor upgrades |
| CPNG | +14.1% | Strong quarter, Korea e-commerce growth |
| ORCL | -8.5% | Post-Q4 capex digestion continues |
| ADBE | -6.3% | Freemium pivot concerns despite beat |
| ADSK | -7.1% | Software sector sympathy |
This broadening is the healthiest sign in the semiconductor complex since the June 5 rout. The rotation is moving from NVDA-only into the picks-and-shovels layer (KLA for wafer equipment, SanDisk for storage) and signals that institutional money is re-entering the AI trade at lower valuations rather than chasing the same crowded mega-cap names.
Key Events Today
| Time (ET) | Event | Note |
|---|---|---|
| 9:30 AM | SpaceX (SPCX) Begins Trading | $135 IPO, largest ever, Nasdaq |
| 10:00 AM | Michigan Consumer Sentiment (Prelim) | Inflation expectations key |
| All Day | Iran Peace Deal Watch | 14-point framework, Tehran pushback |
| All Day | Oracle post-earnings follow-through | $184, down 8.5% |
| Next Week | FOMC Meeting Jun 16-17 | 99% hold at 3.50-3.75%, dot plot |
| Jun 24 | Micron (MU) Earnings | Memory cycle read |
Geopolitical Tracker
US-Iran: Trump claimed a “great settlement” on Thursday, and Iranian state media published details of a 14-point peace framework. The proposed terms include Strait of Hormuz reopening within 30 days, lifted oil sanctions, US military withdrawal, and up to $300 billion in reconstruction funding. But Tehran has not formally approved the draft, and Fars news agency said no initial MoU text has been accepted. Both sides have strong incentives to close: the US wants lower oil prices ahead of midterms, Iran wants sanctions relief and reconstruction. The weekend is the critical window. Oil is pricing in a deal; if talks collapse, Brent reverses toward $95.
Taiwan-China South China Sea: Chinese coast guard vessels have increased activity near Taiwan-controlled Pratas Islands, entering restricted waters on six occasions this year. The standoff intensity remains below Taiwan Strait levels but is escalating. China has pressured Taiwan with increased military presence after the Xi-Trump meeting in Beijing. This is a slow-burn risk that markets are underpricing.
Ukraine: The House passed a bipartisan Ukraine aid bill (226-195), with 18 Republicans defying party leadership. The $1.3 billion security assistance and $8 billion arms sales package now heads to the Senate where it needs 60 votes. Trump has made little progress on his promised peace deal, and Zelenskyy accepted an unconditional ceasefire that Putin rejected.
This note reflects information available as of June 12, 2026, 7:30 AM ET. S&P 500 futures at 7,405 (+0.12%), Nasdaq 100 futures at 29,412 (-0.18%), Dow futures at 51,420 (+0.34%). SpaceX IPO begins trading today at $135 per share. Trump claims Iran peace deal framework reached; Brent crashes to $88, WTI to $84. Adobe Q2 beats and raises but freemium pivot drops shares 6.3%. SanDisk +14.5% on AI memory upcycle. KLA +12.9% on stock split and analyst upgrades. Gold rebounds 2.4% to $4,216. Bitcoin at $63,553. 10Y yield falls 7bp to 4.47%. FOMC meeting next week, 99% chance of hold. VIX at 19.40. For internal use only. Not investment advice.