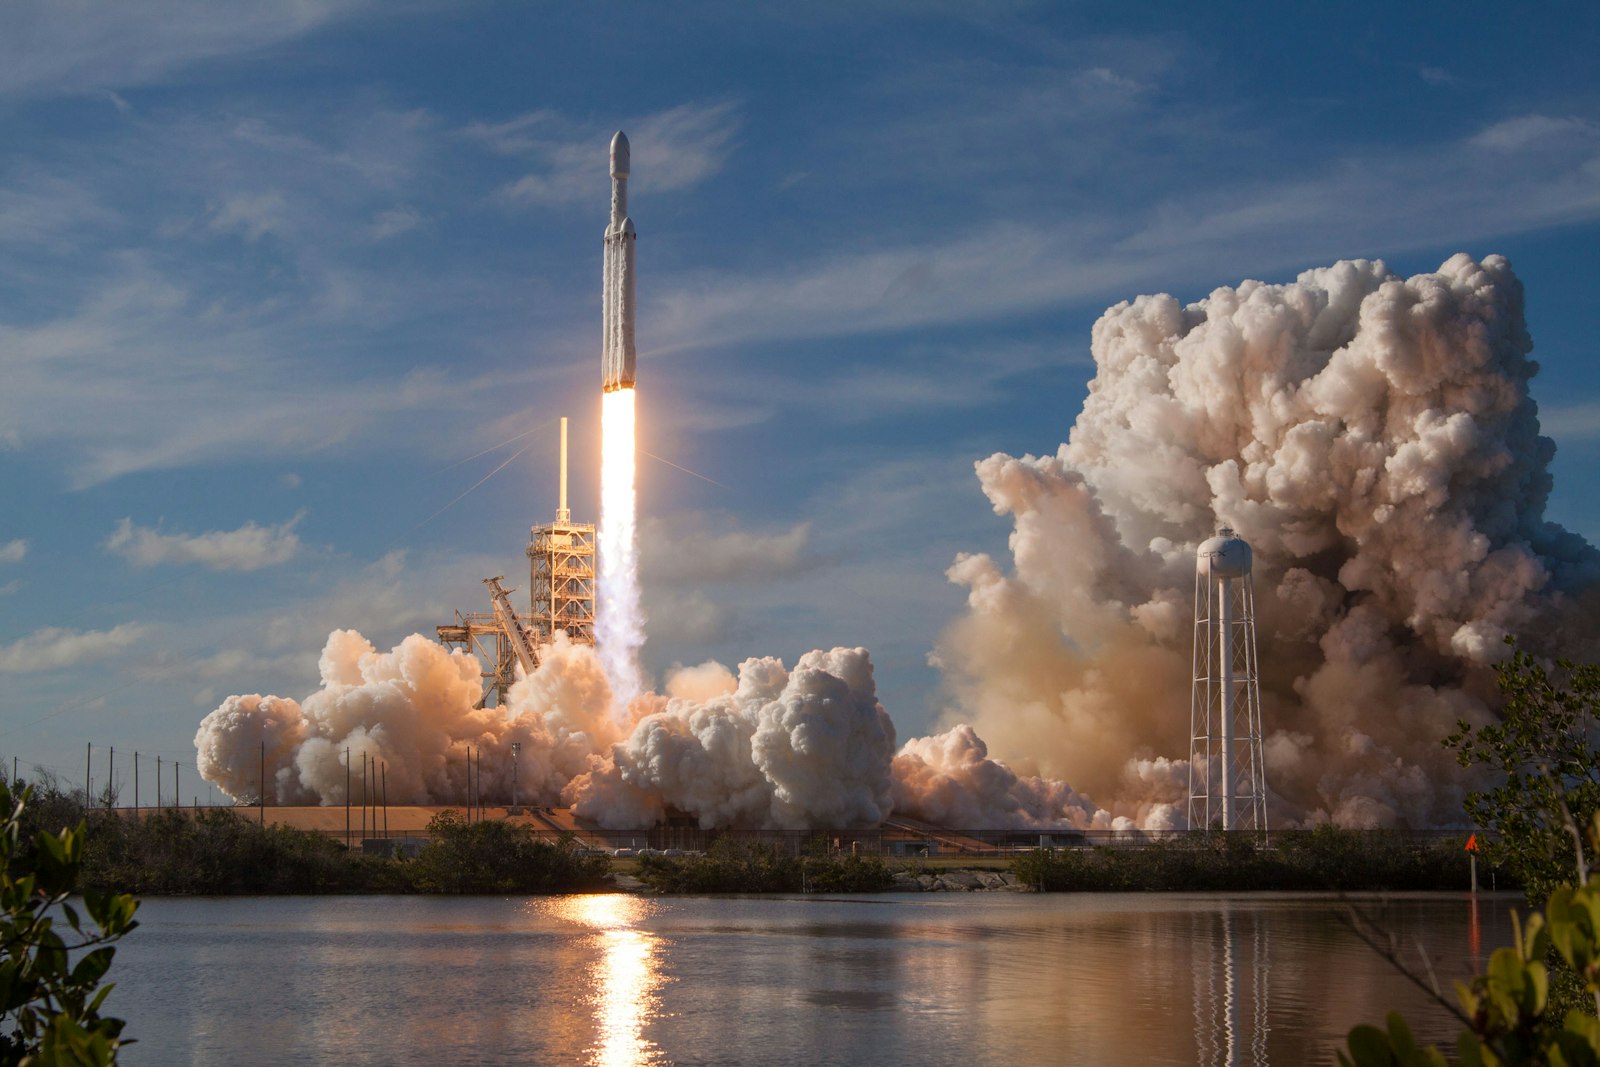
Weekend edition, Saturday June 13. Friday capped a week that reshuffled the macro narrative significantly. The US-Iran peace deal moved from aspiration to near-reality after Pakistan confirmed a “final, agreed upon text” had been reached between Washington and Tehran. Oil cratered on the news, with WTI dropping 3.8% to $84 and Brent falling 3.6% to $88, both at two-month lows. Simultaneously, SpaceX delivered the most successful IPO debut in market history, closing its first day at $161.11, up 19.3% from the $135 offering price, and briefly crossing $175 intraday, making Elon Musk the world’s first trillionaire. The DOJ cleared the $111 billion Paramount-WBD merger without concessions, marking the largest media consolidation ever. All three major indices closed higher for the week: S&P 500 at 7,431 (+0.50%), Dow at 51,202 (+0.70%), and Nasdaq at 25,889 (+0.31%). The VIX fell sharply to 17.68, down from 19.40 the prior session, as geopolitical risk premium deflated. Heading into next week, the June 16-17 FOMC meeting with fresh dot plot projections dominates the calendar.
US-Iran Peace Deal: From Framework to Final Text
The situation escalated quickly from Thursday’s “framework” claim to Friday’s confirmation. Pakistan’s Prime Minister Shehbaz Sharif announced that negotiators had reached a “final, agreed upon text” for a peace deal, the most concrete language yet from any party involved. The draft reportedly includes Iran reopening the Strait of Hormuz within 30 days, lifted oil sanctions, US military withdrawal from forward positions, and up to $300 billion in reconstruction commitments from the US and its allies.
The oil market took the news at face value. Brent plunged to $88.80 and WTI to $84.35, erasing weeks of war premium in a single session. If the Strait actually reopens on schedule, over 12 million barrels per day of transit capacity returns, and crude likely heads toward the mid-$70s. That would immediately relieve the energy shock that drove May CPI to 4.2% and PPI to 6.5%, potentially giving the Fed cover to stay on hold longer than hawkish pricing currently implies.
The skepticism is warranted, though. Iran’s Fars news agency pushed back, saying no MoU has been formally accepted. Nuclear issues are explicitly carved out for separate follow-on negotiations. And factional politics in Tehran could stall ratification even if the text is agreed at the negotiating table. The weekend is critical. Markets are pricing in a deal; if talks collapse, oil reverses hard toward $95+ and the equity rally unwinds.
SpaceX: Record IPO Closes at $161
SpaceX’s Nasdaq debut under ticker SPCX was everything the hype promised and more. The stock opened at $150, jumped past $175 intraday, and settled at $161.11, a 19.3% gain from the $135 offering price. The $75 billion raise at a $1.77 trillion valuation shattered Alibaba’s previous record and instantly made SpaceX the seventh-largest US public company.
What stands out beyond the size is the structure. Musk opted for a fixed-price offering rather than the traditional bookbuild range, and allocated 30% to retail investors, an unprecedented share for a deal this scale. That retail allocation created broad-based demand that likely contributed to the first-day pop. For institutional investors, the index mechanics are now in motion: SPCX will eventually qualify for Nasdaq-100 and then S&P 500 inclusion, triggering waves of passive buying over the coming quarters.
The read-through matters for the broader market. A successful mega-IPO at these valuations signals risk appetite is intact despite the geopolitical backdrop. It also gives investors a direct way to own the Musk infrastructure story (launch services, Starlink, defense contracts) without the EV cycle volatility embedded in Tesla. The question now is whether SpaceX can sustain $161+ or whether first-week profit-taking pulls it back toward the $140-$150 range.
DOJ Clears Paramount-WBD: $111 Billion Media Mega-Merger
The Department of Justice approved Paramount Skydance’s acquisition of Warner Bros. Discovery on Friday without requiring any divestitures, behavioral remedies, or concessions. The $31 per share all-cash deal for WBD creates the largest media company in history, combining CBS, Nickelodeon, Paramount+, CNN, HBO Max, TNT Sports, Warner Bros. Studios, and Discovery Channel under David Ellison’s control.
The DOJ’s clean approval surprised many who expected at least modest concessions given the combined company’s dominance across broadcast, cable, streaming, and theatrical distribution. The $47 billion equity commitment from the Ellison family and RedBird Capital, plus $6 billion in projected synergies, makes the financial structure workable, but execution risk is enormous. Paramount CEO Ellison has committed to closing by September 30, with a ticking fee of several million dollars per day if the deadline slips.
Remaining hurdles are real but narrowing. The UK’s Competition and Markets Authority opened its own investigation on June 9, and the EU has set a July 14 deadline for its review. California’s attorney general also signaled the state may challenge the deal separately. Netflix reportedly lobbied against the merger, which Paramount called “absurd.” WBD shares rose 8.2% on the DOJ clearance.
Consumer Sentiment: Off the Floor, Still in the Basement
The University of Michigan’s preliminary June consumer sentiment index rose to 48.9 from May’s all-time low of 44.8, beating the 46.0 consensus. The improvement was broad-based across demographics, with lower-income consumers showing the strongest rebound as gasoline prices eased from their April peaks. Year-ahead inflation expectations edged down from 4.8% to 4.6%, and the five-year outlook pulled back from 3.9% to 3.4%.
The better reading is welcome but should not be overinterpreted. At 48.9, sentiment remains 19% below a year ago and 28% below where it stood under the previous administration in June 2024. Consumers are slightly less pessimistic, not optimistic. The easing in gasoline prices is directly tied to the Iran peace progress, meaning if the deal falls apart, sentiment will reverse just as quickly. The Fed will note the improvement but will not change policy direction based on a bounce from historic lows.
FOMC Preview: Hold With Hawkish Lean
The June 16-17 FOMC meeting is the centerpiece of next week’s calendar. Markets are pricing a 99% probability that the Fed holds at 3.50-3.75%, the seventh consecutive pause. The real action is in the Summary of Economic Projections and dot plot, which will reveal whether committee members have shifted their rate path expectations in response to the inflation surge.
The macro setup going into the meeting is complicated. May CPI at 4.2% and PPI at 6.5% both point to persistent price pressures, largely driven by the Iran war’s energy shock. But if the peace deal holds and oil continues its descent, those inflationary impulses could fade faster than the data currently suggests. Nonfarm payrolls came in at 172,000 in May, strong enough to eliminate any near-term rate cut discussion. Futures markets are pricing the effective fed funds rate rising to approximately 3.8% by late 2026 and 4.0% by mid-2027, implying the market thinks the next move is a hike rather than a cut.
Global Markets Wrap
Asian markets were mixed Friday. Japan’s Nikkei 225 surged 2.81% to 66,020, propelled by the weaker yen and SpaceX-related sentiment boosting the technology sector. China’s CSI 300 gained 1.2% to 4,777 on improving trade data. But Hong Kong’s Hang Seng fell 0.7% to 24,249, extending its losing streak to seven sessions, its lowest since July 2025, as tech selling and Middle East uncertainty weighed.
European markets closed modestly higher, with the Stoxx 600 up 0.5% and the DAX gaining 0.1% to 24,210. The FTSE 100 added 0.5% as energy stocks declined on the oil selloff while defensive sectors caught bids. The ECB’s 25-basis-point hike to 2.25% earlier in the week continues to filter through European bond markets.
Geopolitical Tracker
US-Iran: Final text of peace deal reportedly agreed. Key terms include Strait of Hormuz reopening in 30 days, sanctions relief, $300B reconstruction. Iran’s Fars agency says no MoU formally accepted. Signing could happen in Europe within days. Nuclear issues punted to follow-on talks. Weekend is make-or-break.
Taiwan-China: Coast guard standoffs near Pratas Islands continued for a sixth incident this year. China’s language on sovereignty claims over the atoll has grown more assertive. Tensions remain below Taiwan Strait levels but the escalation pattern is clear and markets continue to underprice this risk.
Ukraine: House passed $1.3B security assistance and $8B arms sales package (226-195) with 18 Republicans crossing party lines. Bill heads to Senate needing 60 votes. Trump’s promised peace deal has stalled; Zelenskyy accepted an unconditional ceasefire that Putin rejected.
FIFA World Cup: Tournament underway across the US, Mexico, and Canada since June 11. Goldman Sachs projects a temporary boost to US employment and consumer spending, with the largest effects in June. Expected $17.2 billion GDP contribution to the US economy.
Key Events Next Week
| Date | Event | Why It Matters |
|---|---|---|
| Mon Jun 15 | Empire State Mfg, Industrial Production | June manufacturing pulse |
| Mon Jun 15 | NAHB Housing Market Index | Builder sentiment after rate moves |
| Tue Jun 16 | FOMC Meeting Begins | Two-day meeting starts |
| Tue Jun 16 | Retail Sales (May) | Consumer spending durability |
| Tue Jun 16 | Housing Starts & Building Permits | Residential construction trend |
| Wed Jun 17 | FOMC Decision & Dot Plot | Rate decision, SEP, Powell presser |
| Thu Jun 19 | Juneteenth (Markets Closed) | Federal holiday |
Weekend note covering Friday June 12, 2026 close. S&P 500 at 7,431 (+0.50%), Nasdaq at 25,889 (+0.31%), Dow at 51,202 (+0.70%). Iran peace deal text reportedly finalized; Brent at $88.80, WTI at $84.35. SpaceX (SPCX) closed first day at $161.11, up 19.3% from $135 IPO. DOJ clears Paramount-WBD $111B merger. Michigan consumer sentiment rebounds to 48.9. VIX at 17.68. Gold at $4,216. Bitcoin at $63,360. DXY at 99.81. 10Y yield at 4.53%. FOMC meeting June 16-17 with dot plot. For internal use only. Not investment advice.