Monday, June 22, 2026, written pre-market around 7:30am ET. US equity and bond markets reopen today after Friday’s Juneteenth closure, so this is the first live tape since Thursday’s June 18 cash closes, and the screen has plenty to digest. Futures are doing very little after a long weekend, with S&P 500 contracts hovering near 7,569 essentially flat, Dow futures up about a tenth to 52,059, and Nasdaq 100 futures the relative leader at 30,814, up roughly three-tenths on continued AI demand optimism. Underneath that calm surface the cross-currents are real. The US-Iran track produced a constructive weekend, oil and gold are both bleeding as the fear premium drains, the bond market keeps grinding to fresh cycle highs, and the calendar funnels everything toward Thursday’s PCE print. As always with a pre-open note, the levels here can shift by the cash open, so treat them as a setup rather than a settlement.
Top Call: A Quieter Tape With Two Tells, Falling Fear and Rising Yields
The single most important thing for PMs this morning is that the two assets that should fall when geopolitical risk recedes are both falling hard. Oil keeps sliding, with WTI near $75 and Brent under $79, and gold has cracked down to roughly $4,216, off about 0.7 percent and well below the $4,300 handle it carried into the weekend. That is the market voting that the Iran deal is real enough to keep unwinding the war premium, and the weekend delivered the evidence with a signed 60-day roadmap to a final settlement. The catch is the same one we flagged Friday. As the fear bid leaves, the bond market is left staring at a hawkish Fed, and the 10-year is back to 4.50 percent with the 30-year above 5 percent. Our read into the open is constructive but cautious. Lean into the disinflation story through cheaper energy, respect higher-for-longer in rates, and recognize that this is a positioning week, not a conviction week, because Micron on Wednesday and PCE on Thursday are the events that actually move the tape.
Geopolitics: Iran Gets a Roadmap, Hezbollah Becomes the New Flashpoint
The weekend gave the peace trade its next leg. The first round of high-level US-Iran negotiations concluded early Monday in Switzerland with both sides agreeing to a roadmap toward a final deal within 60 days, opening immediate technical talks, and establishing a direct communication line to prevent incidents in the Strait of Hormuz. Mediators described the progress as encouraging. This is a meaningful upgrade from where we stood Friday, when the follow-on nuclear talks had been postponed. The harder issues are now formally on the table rather than deferred, even if they are far from resolved.
Two threads keep this from being a clean all-clear. First, President Trump publicly threatened fresh strikes if Hezbollah does not halt its operations, which reintroduces a Lebanon-shaped tail risk into a situation the market wants to treat as closed. Second, the nuclear file remains a live dispute, with President Pezeshkian insisting Iran will never surrender its right to enrich uranium. For markets the energy-relevant piece, an open and unblocked Hormuz, is the piece that is working, so the immediate price impact of these wrinkles is limited. They matter more as a reminder that headline risk has not disappeared, it has simply migrated from the strait to Lebanon and the enrichment table.
Macro and the Fed: Greenspan Dies at 100 as Warsh’s Fed Faces Its First PCE Test
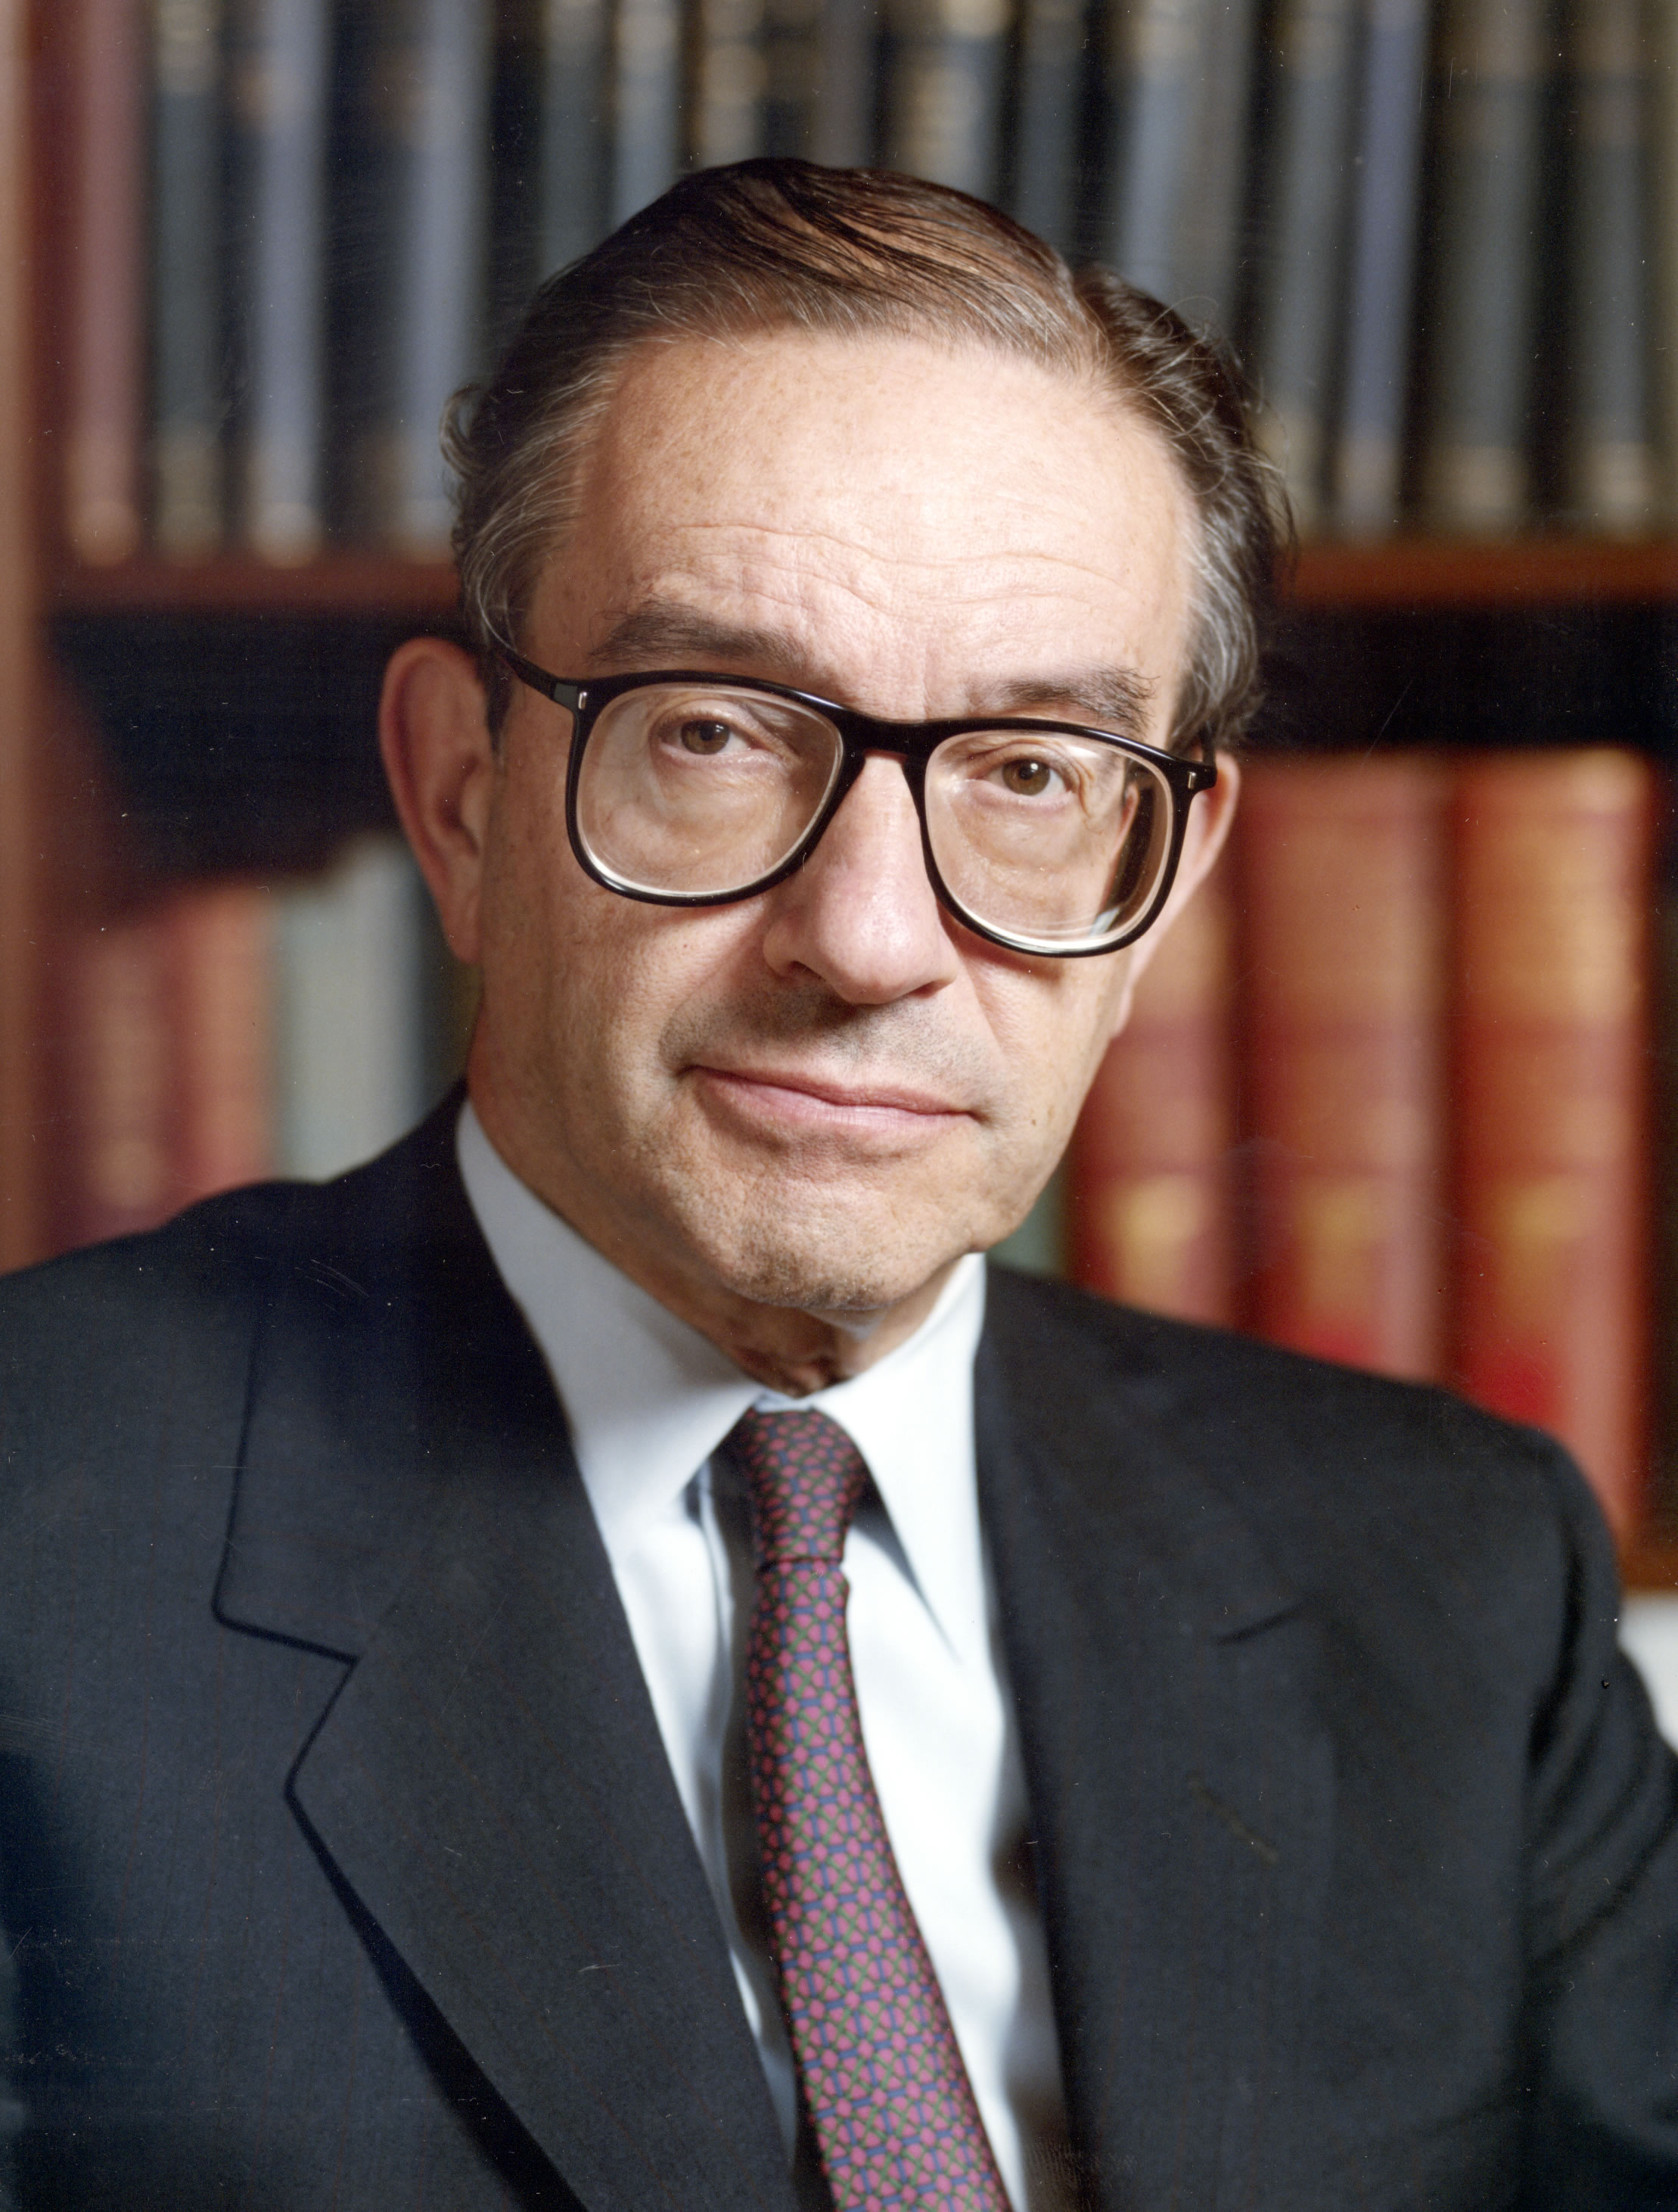
The market lost a towering figure overnight. Alan Greenspan, the Federal Reserve chairman from 1987 to 2006 and the man markets called the Maestro, died Monday at age 100 from complications of Parkinson’s disease. His legacy is the long disinflationary boom he presided over and the phrase irrational exuberance that still frames every late-cycle debate. The timing is poignant, because the institution he shaped is now in the hands of Kevin Warsh and pointed in the opposite direction from the easy-money reflex Greenspan was often accused of. There is no market impact from the news itself, but it is a fitting bookend to a week defined by a Fed that has just deleted the rate cut it was supposed to deliver.
The live macro event is Thursday’s May core PCE, and it lands with unusual weight. Warsh’s first projections lifted the committee’s 2026 PCE forecast all the way to 3.6 percent from 2.7 percent and flipped the median dot toward a hike, so the inflation data now carries the burden of proving whether that hawkish revision was prescient or premature. A hot print validates the higher-for-longer message and pressures the growth complex that has carried the tape. A cooler number lets equities argue the Fed is fighting a ghost. With the 10-year at 4.50 percent and the dollar firm above 100, the rates market is clearly bracing for the former. That tension between equities pricing the peace dividend and bonds pricing a tightening bias is the central story we carry into quarter-end.
Oil: The War Premium Keeps Bleeding Out
Crude extended its slide into the reopen, with WTI down about 0.7 percent near $75 and Brent off roughly a percent toward $78, the softest levels since early March. Oil has now retraced the overwhelming majority of its conflict premium, down close to 40 percent from the April peak, an extraordinarily fast deflation. The pressure is coming from both sides at once. The Hormuz reopening is restoring blocked barrels just as the roadmap reduces the odds of renewed disruption, while OPEC keeps adding supply against a trimmed 2026 demand outlook. The practical caveat is unchanged. Physical normalization through the strait takes quarters not days, so the path lower can stay choppy even as the trend is clearly down.
For portfolios the read-through is the same disinflationary tailwind we keep flagging. Cheaper energy feeds straight into the consumer and into Thursday’s inflation math, which is exactly the offset the economy needs while the Fed leans hawkish. The flip side is that the same cheaper crude keeps draining energy equities, the weakest corner of the market all month, and a fuller Hormuz normalization that tips the global balance toward surplus would keep the sector under pressure into summer.
Semiconductors: Micron Wednesday Is the Month’s Main Event
The chip complex walks into the most important print of the quarter, and we owe a correction on timing. Micron reports fiscal Q3 after the close on Wednesday, June 24, not Tuesday as our earlier notes flagged, since the 24th falls midweek. The setup is loaded. Consensus has clustered higher into the print, with the Street now near $35 billion in revenue, up roughly 276 percent year over year, and EPS around $20, against company guidance of about $33.5 billion and roughly 81 percent gross margin. The estimate range still fans out from about $33.7 billion to nearly $41 billion, which captures how uncertain investors remain about the slope of AI data-center spending after a stock that has run nearly fourfold on the year.
The number we will watch hardest is gross margin, not revenue, because at 81 percent it sits far above Micron’s historical norm and is the cleanest read on high-bandwidth memory pricing power, and margins are the first thing to compress when supply loosens. The bull case is structural. Management says its entire calendar 2026 HBM output is sold out under multi-year price and volume agreements, and Nvidia has certified Micron alongside Samsung and SK Hynix to supply HBM4 for its next-generation Rubin platform, which is now in full production. The competitive backdrop reinforces the theme rather than threatening it. Nvidia’s Rubin launch of six new chips and its multiyear memory partnership with SK Hynix confirm that AI infrastructure demand is still the market’s central organizing force. A clean beat with margins intact validates the AI-memory leadership that drove Thursday’s rebound. Any wobble on margins or 2027 commentary lands hard on a group that has priced a great deal of good news. Super Micro is the early tell on appetite, up nearly 3 percent pre-market near $31.50 on renewed focus on its $7 billion financing package for AI-server expansion.
Healthcare: AbbVie Reopens Big Biotech M&A With a $10.9B Bet on Apogee
The headline deal of the morning is a clean positive for biotech sentiment. AbbVie agreed to acquire Apogee Therapeutics for $135.11 per share in cash, an equity value of roughly $10.9 billion, sending Apogee up about 47 percent pre-market. This is AbbVie’s largest acquisition since the $63 billion Allergan purchase, and the rationale is to deepen its immunology franchise and push into respiratory through Apogee’s clinical-stage pipeline in atopic dermatitis and asthma as the company prepares for Humira’s long tail of erosion. The read-through matters more than the single name. After a month of steady strategic activity, a deal of this size from a blue-chip acquirer signals that financing remains open and that large-cap pharma is willing to pay up for late-stage immunology assets even with the Fed leaning hawkish. Expect a sympathy bid across mid-cap immunology and respiratory names this morning.
Corporate: FedEx Tuesday Is the First Pure-Play Print
Outside the deal tape, the week’s other marquee report is FedEx after Tuesday’s close, its first quarter as a pure-play parcel and logistics company following the June 1 spinoff of FedEx Freight. Consensus sits near $5.91 in EPS on about $24 billion in revenue, and the stock trades close to 52-week highs on the strength of its Network 2.0 cost program. We read FedEx as the cleaner macro signal of the week, a direct gauge of goods demand and trade flow, where Micron is the AI signal. A solid print would reinforce the soft-landing-with-sticky-inflation backdrop the Fed is now leaning into. Paychex also reports midweek and Nike closes the week on June 30, just beyond this window. Earnings were otherwise light overnight, with no major coverage company reporting before the bell.
UK Politics: Starmer Steps Down, Sterling Whipsaws
The notable overseas political story is Keir Starmer announcing his resignation as Labour leader and Prime Minister. Nominations open July 9 and he stays in office until a successor is chosen, with Andy Burnham the early front-runner. Sterling whipsawed, initially soft and down about 0.3 percent against the dollar before recovering back above $1.32 on speculation that Burnham could run unopposed and shorten the uncertainty. The episode is a domestic UK story with limited direct read-through for US assets, but it adds a layer of political noise to a European session that was already drifting lower.
Asia and Europe Overnight
Asia was a study in divergence. Japan was the standout, with the Nikkei 225 surging about 2 percent to 72,648 and pushing to fresh highs on the familiar mix of a weak yen and surging exports, shrugging off the Bank of Japan’s recent move to 1 percent. Greater China went the other way as it returned from the Dragon Boat holiday. Hong Kong’s Hang Seng fell about 0.7 percent to 23,769 with the Tech sub-index off more than a percent, and the mainland was modestly lower with the Shanghai Composite near 4,076 and the CSI 300 around 4,725. China rare-earth and export-licensing policy is back in focus, with advanced sub-14-nanometer chip and next-generation memory materials now subject to case-by-case review, a slow-burn overhang for the global semiconductor supply chain. Europe opened on the soft side without much of a US lead, with the Stoxx 600 down about a tenth, the DAX off two-tenths near 24,950, and the CAC weaker by half a percent, while the FTSE 100 held up better against the political backdrop in London.
Geopolitical Tracker
US-Iran: First round of high-level talks concluded Monday in Switzerland with a 60-day roadmap to a final deal, immediate technical talks, and a Hormuz communication line. The strait stays open and tankers are transiting. Tail risks have migrated rather than vanished, with Trump threatening fresh Hezbollah strikes and the uranium-enrichment dispute still unresolved.
United Kingdom: Keir Starmer resigning as Labour leader and Prime Minister. Leadership nominations open July 9, with Andy Burnham the front-runner. Sterling volatile but recovered above $1.32. A domestic story with limited US spillover.
Ukraine-Russia: Structurally unresolved and overshadowed by the Iran outcome. Combat continues along the eastern axes and ceasefire talks remain stalled. A pending US security-assistance package is the item to watch for headline risk.
Taiwan Strait and South China Sea: PRC coast guard pressure near the Pratas Islands continues at a low simmer with no major escalation. The incremental pattern persists but stays contained.
Quick Take: Micron (MU) Q3 FY26 Preview, Reports Wednesday After Close
| Metric | Consensus / Guide | Why It Matters |
|---|---|---|
| Revenue | ~$35.0B (Street); ~$33.5B (co. guide) | ~276% YoY growth; range $33.7B to $41B shows AI-spend uncertainty |
| EPS (non-GAAP) | ~$20.0 (Street); ~$19.15 (guide) | Up from $1.91 a year ago; operating leverage on HBM |
| Gross Margin | ~81% | The single cleanest read on HBM pricing power |
| 2026 HBM | Sold out, multi-year contracts | Structural demand vs. spot-driven past cycles |
Our Take: This is the swing vote on whether AI-memory leadership can carry the tape into quarter-end. We are watching margins above all, because revenue can beat on volume while a margin slip would signal the supply-tightness story is already loosening. A clean beat with 81 percent margins intact and constructive 2027 commentary should pull the group higher and validate Thursday’s rebound. Any softness on margin or forward tone lands hard on a stock that has nearly quadrupled this year, so we are constructive but would not chase it into the print.
Key Events Ahead
| Date | Event | Why It Matters |
|---|---|---|
| Mon Jun 22 | US Markets Reopen | First live pricing of the signed deal and hawkish Fed together |
| Tue Jun 23 | FedEx Q4 FY26 (FDX) | First print as a pure-play parcel name; goods-demand gauge |
| Wed Jun 25 | New Home Sales (May) | Housing read after the 15% starts plunge |
| Wed Jun 24 | Micron Q3 FY26 (MU), after close | The AI-memory verdict; ~81% gross margin is the key tell |
| Thu Jun 26 | Core PCE (May) | The Fed’s preferred gauge after the SEP lifted 2026 PCE to 3.6% |
| Thu Jun 26 | Final Q1 GDP, Jobless Claims | Growth and labor check into quarter-end |
| Tue Jun 30 | Nike Q4 FY26 (NKE) | Consumer and China demand read into July |
Monday pre-market note, June 22, 2026, drafted around 7:30am ET. US equity and bond markets reopen today after Friday’s Juneteenth closure; levels shown are pre-open futures and overnight prices and may shift by the cash open. Thursday June 18 cash closes were S&P 500 7,500.58, Nasdaq Composite 26,517.93, Dow 51,564.70. The US-Iran talks concluded Monday in Switzerland with a 60-day roadmap to a final deal and a Hormuz communication line, though Trump threatened fresh Hezbollah strikes. Alan Greenspan died at 100. AbbVie agreed to buy Apogee Therapeutics for $10.9B ($135.11/share cash), Apogee +47% pre-market. WTI near $75.30, Brent $78.40, oil down roughly 40% from the April peak. Gold around $4,216, Bitcoin near $64,100, DXY 100.20, 10Y 4.50%, 30Y above 5%. Nikkei +2% to 72,648; Hang Seng -0.7% to 23,769. Micron reports Wednesday June 24 after the close, FedEx Tuesday June 23 after the close, with core PCE Thursday. For internal use only. Not investment advice.